
After a stellar 2025, 2026 has seen a pivot away from precious & critical minerals, as we await a new pivot
From the standpoint of the most precious metal of all, gold, the stock market has been the star of 2026. All year we anticipated a bottom to be put in at/above the green shaded box. If that bottom is in, that is exactly where it was forged. However, later in the article you will see a caveat to this view.

Meanwhile, let’s hear it for the bloated world of equities! AI and its enabler, the Semiconductor sector, have done the heavy lifting while companies servicing other aspects of the economy struggle. But in general, the pig levitates, 2026 style!

Semi is again putting on the push to lead the stock market higher. I own (and display in NFTRH) several Semis relevant to the still-manic AI industry. Not as an investment at this time. Just as a trade with the current market internals.

I have been long Semi and other sectors of the market all year, as NFTRH tracks its sometimes head-spinning internal rotations.
But the rotation that is most important began early this year and is still in effect in the short-term. The SPX/Gold ratio bottomed on January 29th and has since risen 45% (gold topped out per the chart at top).
To put it in stark visual context, later in the article we’ll dial out to a long-term view using the 30yr Treasury yield ‘Continuum’ chart (our road map to the 2022 pivot to the new macro) and the long-term SPX/Gold chart.
The macro is “new” because the bust-out of a secular downtrend (of disinflationary signaling) in long-term Treasury yields projects difficult times ahead. Not just for consumers and the wider economy, but also because policymakers no longer have a primary tool (efficient bond market manipulation) at their disposal every time they wish to rig the picture to thwart negative market outcomes.
Here I interject that I’ve been anticipating Bessent’s ability to rig a very temporary Goldilocks environment that would continue to flatten the yield curve and pressure or at least cap long-term yields. Instead, the 10yr yield is seeking escape velocity while the yield curve re-thinks its flattening plan. If the curve re-steepens, it does not necessarily negate the short-term bullish stock market view, but it would likely pull in the time frame of gold’s coming pivot vs. stocks.
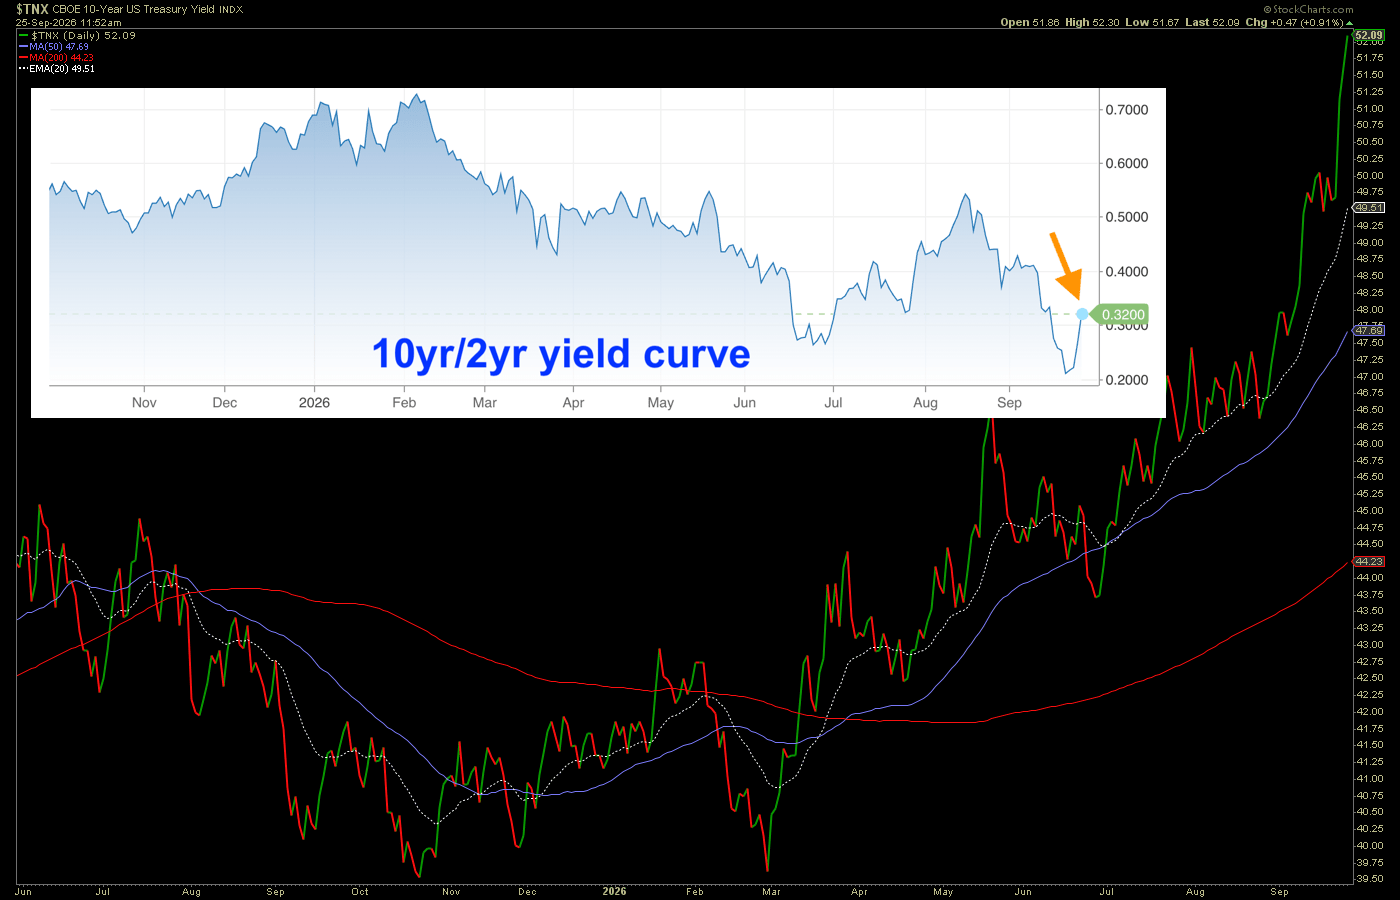
The Broken Continuum
The former disinflationary signaling in bonds (old macro “Continuum”, circa 1980-2022) was the backbone by which Fed and Treasury manipulators policymakers painted the macro at will. They painted away inflation signals (Operation Twist), they painted in economic rescue (of “too big to fail” institutions that played large parts in wrecking the system and the economy to begin with), and…
…as the longest-term outcome, they painted asset prices higher and higher * with each bailout operation. In other words, inflation with a green light provided by the decades-long downtrend in yields. These episodes boosted asset prices, enriching asset owners and impairing those who need, but less and less can afford those assets (and service providers hiking prices due to inflationary effects). Inflation-making was official policy and it was systematic.
All gone now, boyz. The country has been ruined and now we had better hope there is such a thing as a Kondratieff Winter (ending at a point as bad as it gets) and K-Spring (ahead). Because if not, society is so screwed, existentially.

* And by extension, they painted today’s ‘rich exponentially richer, not rich poorer’ dynamic that has logically brought on socialist sentiment on the left and awareness and hatred of billionaire Oligarchs on the left and right. That, in turn, has prompted a surveillance state because our billionaire friends would not want brewing ‘off with their heads!’ sentiment, now would they?
SPX/Gold
Back on the main theme. Stocks have been bullish in gold terms in 2026. But long-term, this is a final kiss goodbye for the stock market, in gold terms at least. We anticipated a sharp rebound in SPX/Gold after 2025’s excessive move the other way. It’s a macro relief valve. And man is the paper/digital world of grift and greed putting on a show.
But that is all this was projected to be, a show. A shit show to right-size peoples’ expectations. The herd will be aligned poorly again, FOMO’ing AI, Semi and other sex stars when the new macro turns back to its dominant trend, which is in favor of gold/precious metals, which tend to lead commodities and resources (current interest especially in the now-geopolitically sensitive critical minerals area).
As to the chart, I’ve imagined a bullish Inverted H&S that theoretically could send SPX/Gold higher for a final burst. Casino patrons are advised to have their heads screwed on straight if it happens and when it tops out. The opportunity to favor gold and quality items within the global inflation trades will be set up on a silver platter (pun not intended, but if the shoe fits…).

Bottom Line
Once again I let you know that the above is not written by some robo-goldbug, always touting. No, it is written by someone who took puts on silver at the start of the year, hedged gold stocks off and on all year and has been long stock sectors that have been favored by the ongoing market rotations all year. There are many public instances of my public writing and X posts to back this up, so if you need proof, go search for them. I’m not going to make that [promotional] effort.
The bottom line is that 2026 has seen a resurgence in stocks vs. gold. I have drawn a best (or depending on your view, worst) case scenario showing that a bull pattern can still express upward in SPX/Gold. Perhaps toward year-end. But a pivot point of opportunity is upcoming. Unfortunately, most will miss it because they will have been swayed to believe the 2026 stock market is real.
It is not real, in gold terms. The opportunity is for conventional stock market patrons to take this last chance and pivot away from a pro-stocks bias. The other opportunity, for those of us who have been patiently waiting, ‘playing’ stocks but anticipating the pivot back to the real macro, is to find and get long the best exploration, royalty and producer candidates in the precious metals and critical minerals areas.
As for gold the metal, it’s a heavy lump of value that does not care about cycles, rotations or sentiment. It is simply a long-term store of value. With its future valuation likely to be marked up significantly.
In the opposite direction of the US stock market’s revaluation, which will come from nosebleed heights. In this case, as divided by M2. Gold has a lot of catching up to do in that regard, and in this new macro.

For “best of breed” top-down macro analysis and market strategy covering Precious Metals, Commodities, Stocks and much more, subscribe to NFTRH Premium, which includes a comprehensive weekly market report, detailed NFTRH+ updates and chart/trade setup ideas, and Daily Market Notes. Receive actionable (free) public content at NFTRH.com and subscribe to our free Substack.
