
The anticipated Goldilocks macro appears to be in effect, absent some classic signals
In anticipating a Goldilocks macro, we (NFTRH) planned for a disinflationary phase, with nominal Treasury yields pulling back and yield curves flattening. A “just right” mix of economy okay and inflation signals muted. This would also include a strong US dollar.
USD Plays Ball
We’ve got the strong US Dollar, which is ticking a new high in its base breakout this week. This is as it should be. As a side note, the Gold/Silver ratio, while not overtly bullish, is firm and a firm GSR that does not get impulsive to the upside is also consistent with a Goldilocks macro. Silver will take over when inflation signals erupt and/or USD starts losing support from a hawkish Fed.

But Treasury Yields!
Yes, Treasury yields. What of them? They are not rising because of inflation. The Fed has adopted a hawkish stance on the short end and the “real” 10yr yield is rising (to its highest level since 2008, in fact).

That, along with this graph showing the 10yr breakeven inflation rate going sideways since 2022 imply a picture of inflation under control.

It’s not inflation. It’s the effects of war, trade policy and general global discord. A spanner in the works of what used to be the intertwined US and global economy.
As for the yield curve, it flattened as anticipated. But then a strange thing happened on the way to a nice fairy tale. A spike toward re-steepening has come about. It remains to be seen whether the flattening will resume.
A classic Goldilocks macro would feature a flattening yield curve. Here the 10yr/2yr is seen spiking as the market sees a likely interim top in yields and weakening Fed hawk sentiment.
A re-steepening of the curve could see gold and the things it leads (miners, silver, commodities) find their footing and participate. A re-flattening, not so much. As with the projection for USD in the other (downward) direction, when the Fed does flip dovish, the curve should steepen [bull steepener] and gold should lead the future ‘inflation trades’.
[for a kicker, see the next segment below]
This Just In
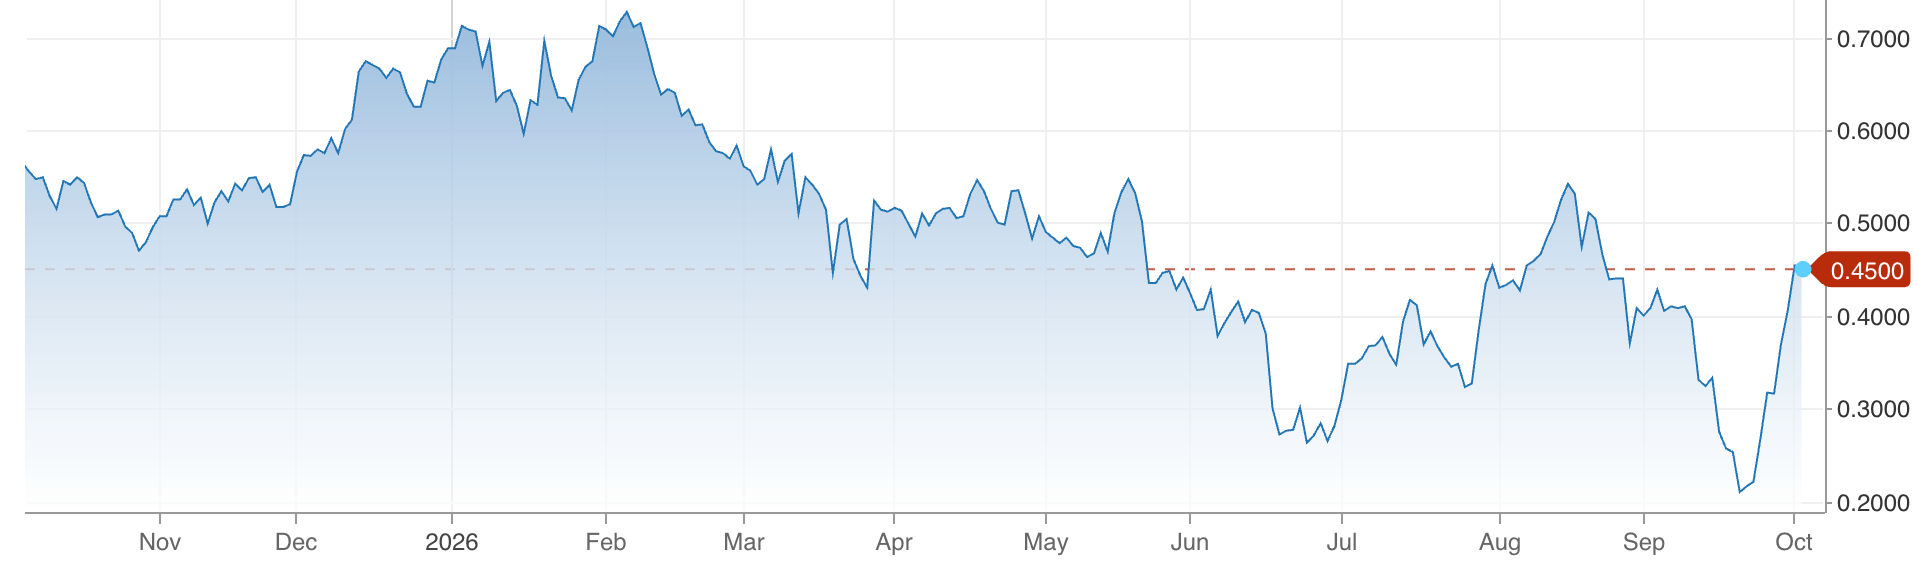
While writing the above, we just so happen to have had an important macro indication hit the screen. September Payrolls came in at 29k vs. 84k expected and 162k for August. Goldilocks, anyone?

Because here in Wonderland people not finding jobs = muted inflation (that actually was not even in play) = implied Fed dovishness (when combined with Wednesday’s lower than expected PCE Index report) + a still firm ISM (Manufacturing, benefitting from the AI-buildout craze) =

Because of course it does!
If the ‘Fed dove’ implications of PCE data and this jobs report play out, USD will probably flop and paint its base breakout as a bull trap. In my opinion, ‘they’ want a weak USD, after all. ‘They’ have been pretending not to want that lately because of the pressure exerted by the bond market rebellion. In my opinion, informed by >>>
Tin Foil

And of course this pleasant phase of macro relief was going to shoe-horn into the run-up to the mid-term elections.
Folks, I did not know how they would pull it off, but I felt that Bessent was in close, shall we say ‘coordination’, with Warsh on a plan to stop yield curves from [bear] steepening further (nominal long-term yields rising harder than short-term yields). A sort of mini Operation Twist to sanitize whatever it was (not inflation) that the bond market was in a tizzy about. Like ever-increasing $Trillions in national (the peoples’) debt, perhaps?
Not to get political, but let’s be real. Trump was going to start reducing the debt on day 1. Trump was going to keep us out of all foreign entanglements. Trump was going to drop tariffs on trading partners so they will pay their fair share, to the benefit of the American public (with dividend checks and all). Now it’s talk of giveaways (paid from the massive bag of the peoples’ debt) to favored constituencies, including a $5000 per person kickback for voting Republican.
Talk about socialism. It’s a good thing Dear Leader tends to be full of hot air.
It’s All Good!
But we are market participants, and this manager prefers to play the grift rather than be victimized by it. One way or another, the macro has been painted favorably. For a moment in time, at least.
Our favored areas – for reasons beyond the scope of this article – as noted for NFTRH subscribers, are big Tech and the beaten down Semiconductor sector. Other areas of the risk-on market should work as well.
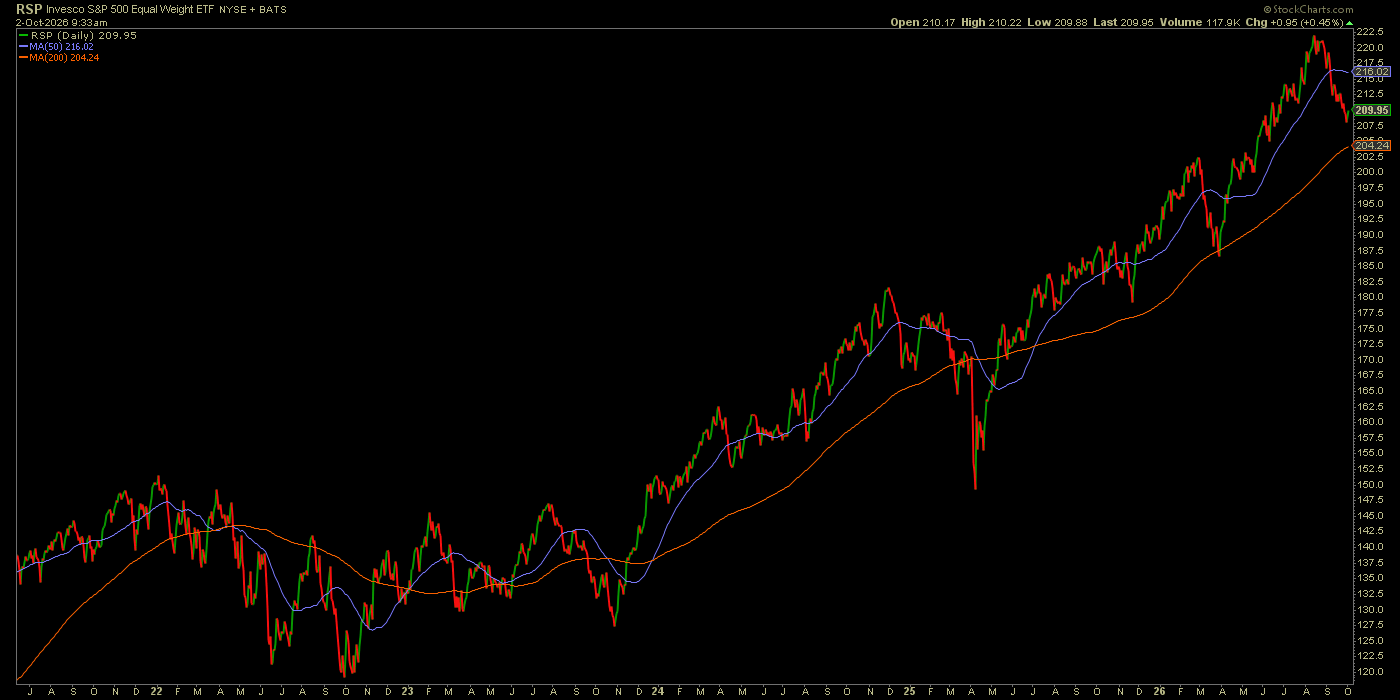
The market has been thinning out internally, despite the feel-good picture on the surface. For example, equal weight SPX RSP) is in the tank vs. headline SPX (SPY) and its most popular large caps.

However, nominal RSP and many other broad market trackers are merely in normal corrections. A real bear market in stocks would only be indicated if these items lose their major uptrends.
Bottom Line
Meanwhile, cue Old Turkey: “It’s a bull market, you know.”
What’s more, despite valid concerns about nosebleed valuations and many other issues, this market continues to indicate ‘bull’ (read into that as you may). Also, there is this, which was included in NFTRH 934 last weekend. Today is October 2nd and the real (Equal Weight SPX, NYSE, Small Caps, Value Line Geo index, etc.) stock market has been in correction for 1.5 months now.
So far the (equal weight) SPX mid-term pattern is on message. If it stays on message that message is bullish into year-tend.

For “best of breed” top-down macro analysis and market strategy covering Precious Metals, Commodities, Stocks and much more, subscribe to NFTRH Premium, which includes a comprehensive weekly market report, detailed NFTRH+ updates and chart/trade setup ideas, and Daily Market Notes. Receive actionable (free) public content at NFTRH.com and subscribe to our free Substack.
