
If ever there was a week for the market to go my way and in line with current short-term analysis, this is that week (the move from hell drags on, but gets better each day as we settle in).
While we have anticipated a very positive risk/reward and bottom/bounce situation in the precious metals, it is only getting into gear this week. Now, if it’s just a tradeable bounce, that’s one thing. But keeping tabs on the internals will help us see if it is something much more. It will also help us fine tune the 2003-2007 inflation trade analog, timing-wise.
These ratio charts will help in determining whether gold stocks are “nothing special” (per the ’03-’07 analog view) or “once again special” amid a counter-cyclical phase. For that we’ll look at gold and its miners vs. copper and its miners and gold in relation to inflation expectations.
These charts use ETFs instead of the related indexes and assets.
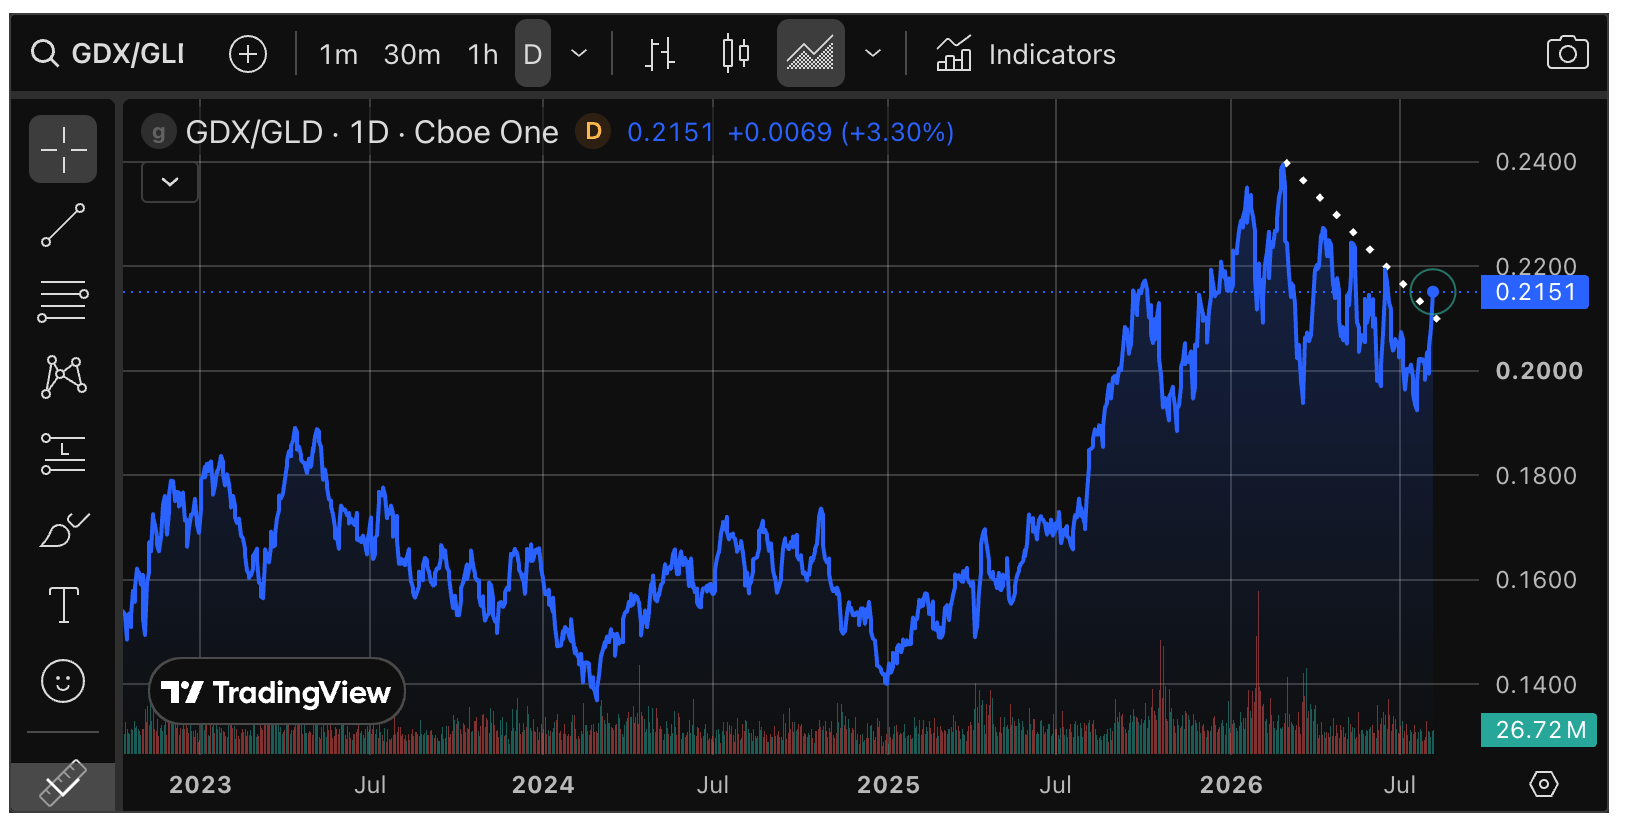
Let’s start with the proxy for the HUI/Gold ratio, GDX/GLD. Today it is making a move to flip the sector internals positive. Now follow through!
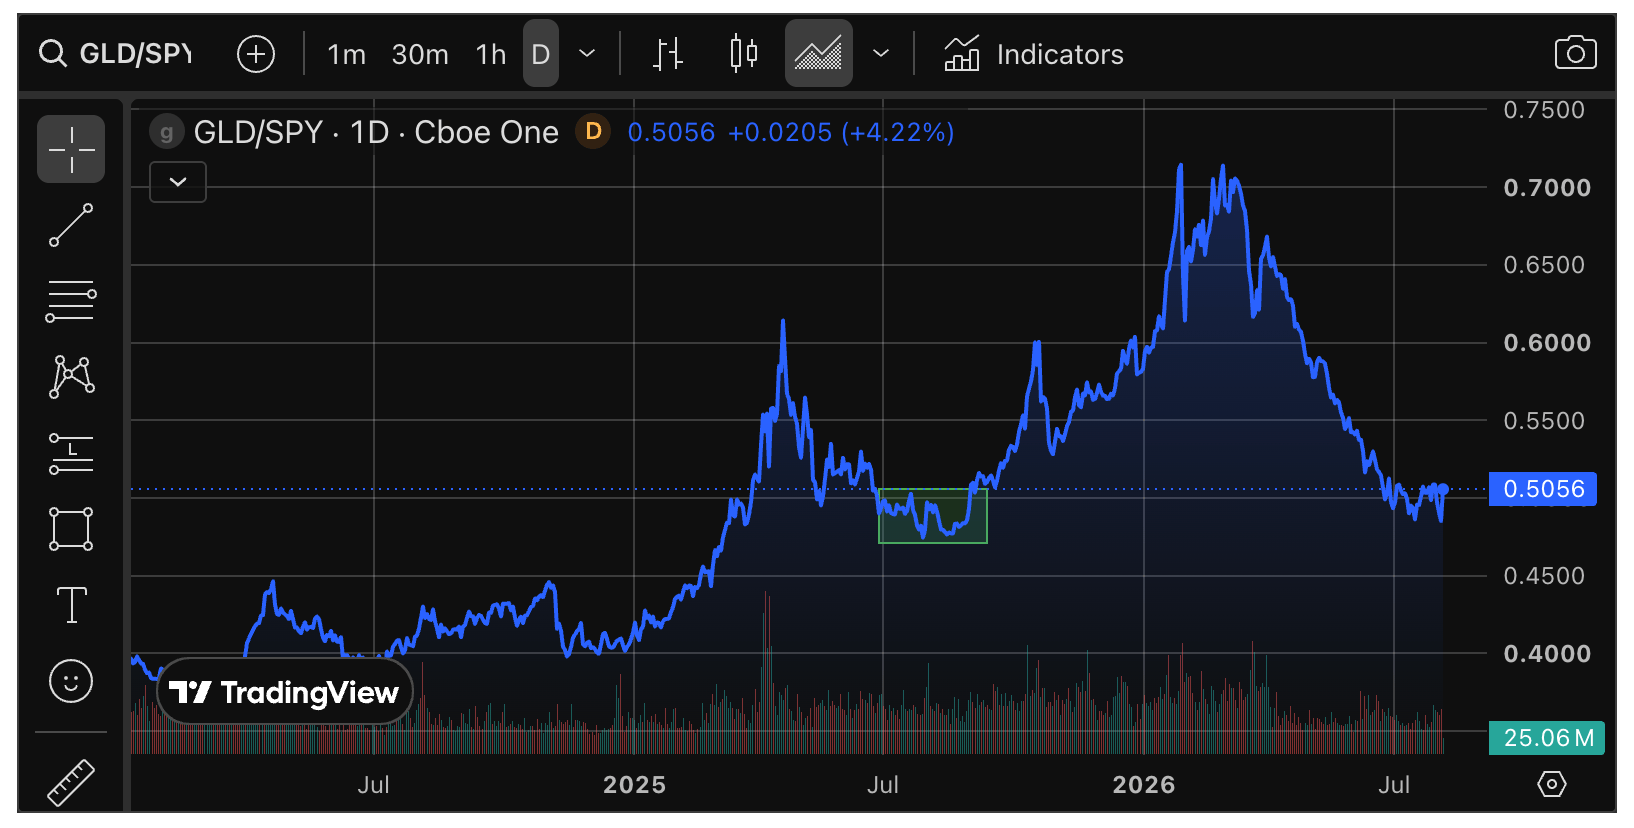
Gold (GLD)/SPX (SPY) should be getting croaked with SPX hitting new all-time highs. But no, it’s hanging in there at our target for a bottom. I see this as quite positive for gold going forward. Or at least risk in gold is much lower than risk in broad stocks.
Gold/Oil looks to be bottoming, a serious positive for gold mining sector fundamentals.

As for macro fundamentals, if the GLD/RINF ratio also holds and turns up that will be extremely positive in a macro-funda sense, and could start to alter our course back toward a counter-cyclical disinflationary or stagflationary view rather than a cyclical inflationary one like 2003-2007. Again, this would feed the ‘gold stocks something special’ narrative, much like in 2025, if a strong new rise were to come about.

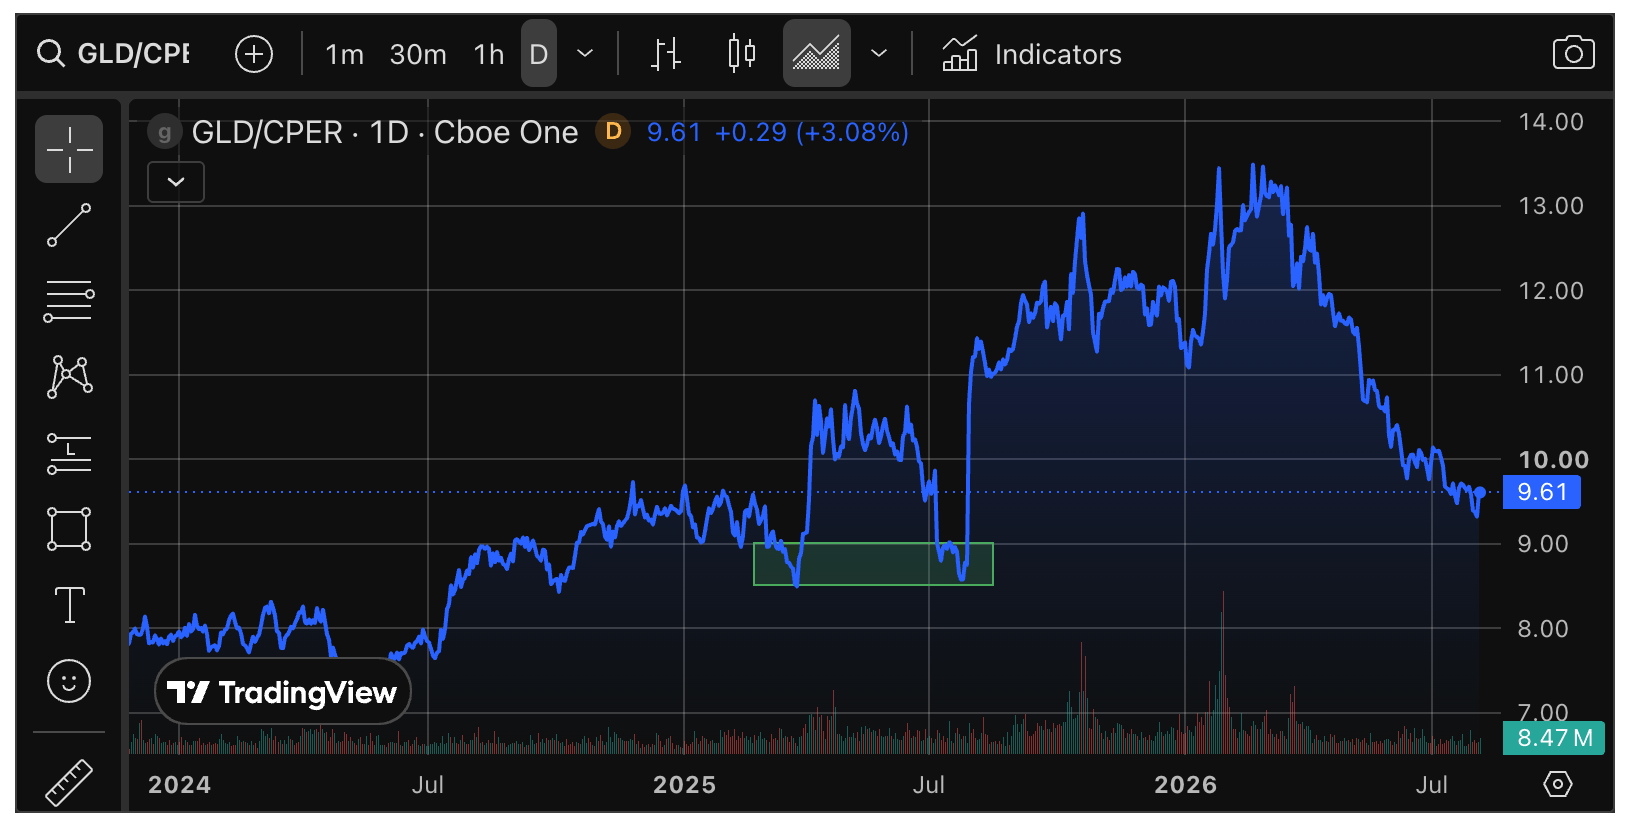
So now we come to the metal that is more counter-cyclical vs. the metal that is much more cyclical. Gold/Copper is at a higher low. If this bottoms and heads for new highs it would be a negative forward sign for the global economy (likely in 2027).
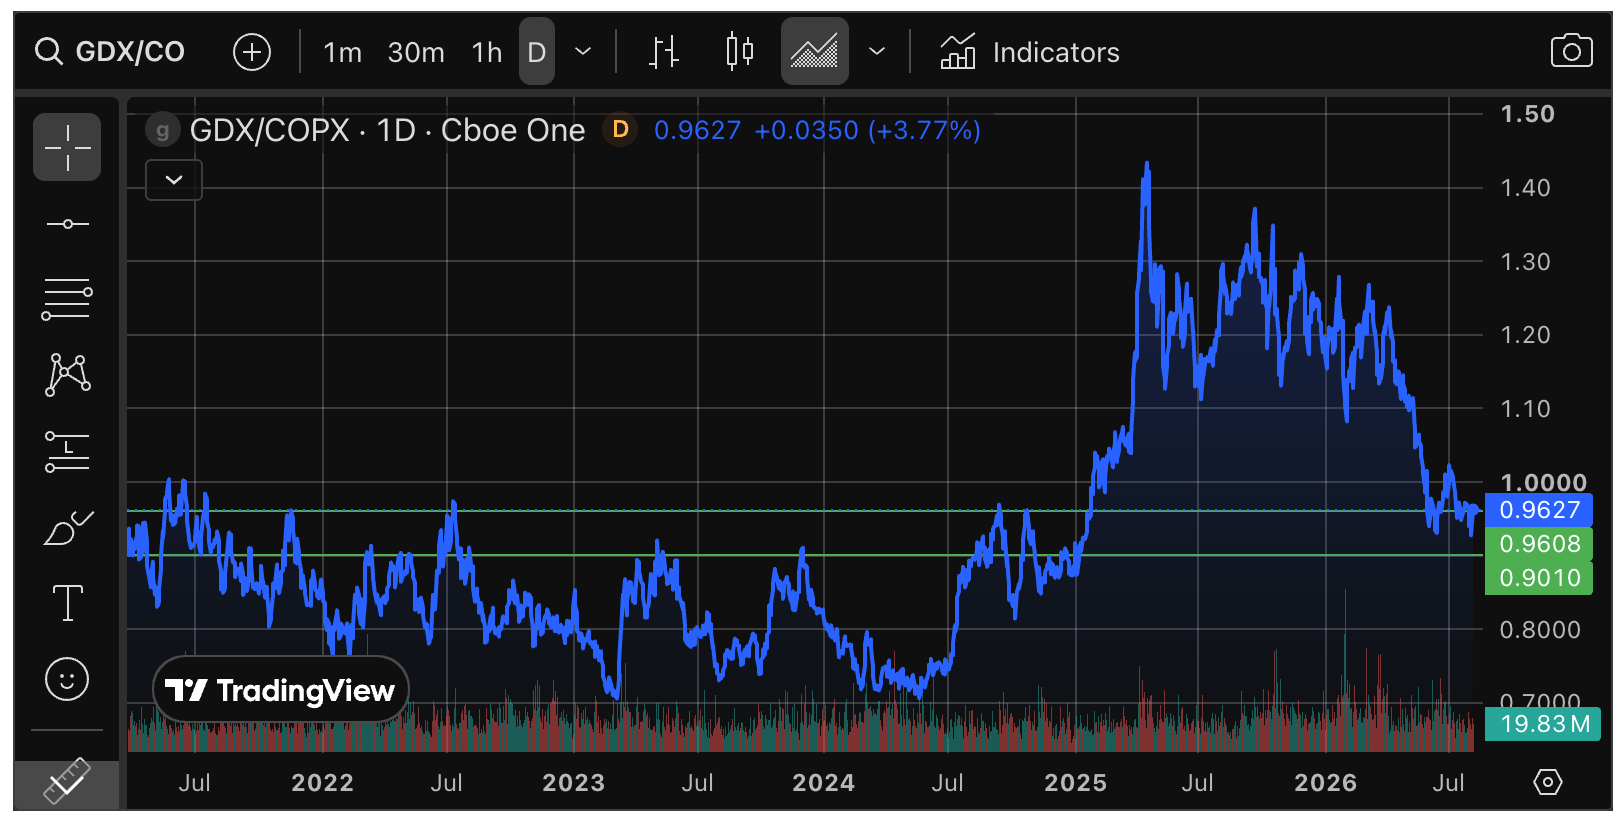
So let’s update the situation in the counter-cyclical miners vs. the cyclical miners. The GDX/COPX ratio was originally expected to test the base breakout, and that is exactly what it is doing. However, our original plan – before getting hopped up on the 2003-2007 inflation trade analog – was for this test to hold support in preparation for the next counter-cyclical phase.
Bottom Line
While we have other analytical points (including the deregulated banking sector) hinting at a bullish but under-performing (vs. commodities) gold price, ala 2003-2007 (with gold miners “nothing special”), the original plan was for a resumption of a counter-cyclical macro and gold miners “oh yeh, special”.
If gold vs. inflation expectations, oil, copper, etc. turns up the GDX/COPX ratio will also turn up into a counter-cyclical macro with economies under stress. That is in my opinion what Bessent and Warsh would inflate into. It was our original plan before other indications had us considering whether the inflationary macro may start sooner rather than later.
At this time, I go with our ‘most markets bullish’ to/through November plan, but I lean toward the next phase being counter-cyclical and disinflationary, which would spur on our heroic policymakers (along w/ deregulated banks) to bring on the next, likely severe inflation phase.
In other words, in the near-term I am mentally fading the 2003-2007 scenario in favor of a still bullish environment for most items, but a uniquely bullish environment for gold stocks. Later would come the big inflation phase.
My writing may be confusing because the macro is so involved and subject to inputs coming from all angles. Please ask questions (here in the comments or by email) if I need to clarify anything. The distinctions matter little right now, because it’s mostly bullish out there. But they will be important going forward. We’ll keep a good watch on the ratios above and more.

Thanks for the update Gary!
Sure thing, Pete.
We never did (never will, or not yet?) hit the GDX=65 point I was waiting for in order to star pushing significant money back onto the table like in 2025. I still feel safer, as a non-trader, sitting on my hands/profits although I am subject to FOMO like any human. Sold all GDX above 100, and nibbled a small amount in my kids taxable UTMA accounts at 75, but now I am frozen in place again. A lot of your excellent analysis lends to buying in tax-free accounts while buying in taxable accounts is more difficult when the ratios and feel of your weekly letter seem to shift a bit more mercurially. Based on your cash allocation I am guessing you feel the same?
My cash position is being reduced/deployed slowly, systematically. But I have to stress something here. I will not tout gold stocks. I will not obsess on them. I will not operate as if there are no other sectors in the world. The analysis has been consistent. Risk in the precious metals has been low, and we have talked about a likely bounce. In this update we talk about what to look for to see if we get more than a bounce. Like a new bull market leg. It is my hope that people will follow the analysis, not what I may (and likely will not) be jumping up and down about.
–
As for mercurial shifts, look to the market. I do not shift. I discuss (rightly or wrongly) what I interpret the market to be saying. It shifts? I shift. Otherwise, I become a tout, showing my hand as a perma promoter of my bias (as a PM bull). The bottom line is that GDX has broken out of the downtrend, is hinting to start leading gold (not quite yet), and may well be on the next bull move. With all the talk of low risk and even reco’ing gold stock bulls start nibbling a couple weeks ago, I don’t think waiting for some lower price (which I admittedly held open as possible) is implied.
–
Bottom line: gold stocks are bulling. Commodity stocks are bulling. Broad stocks are bulling. That is my focus. This update lays some groundwork for what we’d want to see in order to focus even more on gold stocks. Meanwhile, I’ve been buying them… along with non-gold stocks.