

Summary
A brief summary of the work done in this week’s report and in the updates and reports leading up to this point. Please read the detailed report for the complete picture. There are many granular details that cannot be summarized so briefly.
[new comments italicized]
Precious Metals (bull market)
Anticipating one final decline to a good low. That could be an epic buying opportunity. Indications point down and the time window appears shortening. Capitulation needed, and question remains of interim bounce first.
[the bounce has begun and is expected to be only that; although we will watch for the alternate “resumed bull” option]
US Stock Market (bull market)
SPX, having benefitted from internal rotation while the likes of SOX and NDX have developed bearish situations, finally made a little crack last week. If this correction is worth its salt it should eventually affect most sectors and drop SPX.
[so far, so good]
Global Stock Market (bull market)
Barely hanging on to upside trend change relative to US. If the USD has more upside, global under-performance to US should have more downside. When USD tops, more global exposure would be a sound strategy.
[global, and especially China/Asia/EM along with Australia and Canada would be the focus if/when USD finishes its bull]
L/T US Treasury Bonds (bear market)
Bonds are hinting bullish again. Just a hint. But if that plays out it would be 100% in line with our view of a disinflationary phase. Anticipating a bounce or rallly, not a new bull market.
[wrong, sir… so far at least]
Commodities/Resources (bull market)
Not time yet to position with any conviction, in my opinion, as the Fed plays hawk and market liquidity is constrained. But with FOMC on the horizon, if they weaken and USD weakens, we could see commodity and resources stocks rally hard.
[Fed not projected to weaken after a week of war and price increases, indeed, FOMC could hawk (in talk or action), support USD in the short-term and offload the inflation-making to the commercial banks]
US Dollar (short-term bullish, long-term bull market, post-2008)
US Dollar (mega long-term bear market)
USD is still in an intermediate rally within what we have been calling a long-term technical bull market. As such, we flip to shorter cyclical bull joining that “long-term” bull. This is technically speaking. As we divine what Warsh and Bessent may be cooking up (USD bearish as per 2003-2007 or through genius manipulation not yet apparent, USD bullish?).
[regardless of the details from Manip Central (Warsh/Bessent), bullish USD near-term, anticipating very bearish long-term]
Admin: As noted previously, we are moving next weekend and so NFTRH 926 will be abbreviated and published on Friday or Saturday.
Wrong On Bonds?
It happens. Sometimes things don’t go as planned. The plan was for an interim disinflationary environment to support Goldilocks or perhaps, instigate a deflationary liquidity scare before the next inflationary phase drives yields up again and bonds down further. So far, it is still inflation in the headlines, and no “interim” anything.
I could blame the war and its driving of oil prices and other knock-on prices and costs, but that is too much like an excuse. In market management, wrong is wrong for whatever reason. Only being right on the macro view will suffice.
The Treasury bond market is trying to impose good practice upon our monetary and fiscal manipulators by handcuffing them on yields. The Fed is not going to cut the Funds rate this week. Indeed, now 34% of CME Group traders think the Fed will raise the Funds rate this week. That’s a big bump, folks.
All due caveats about CME’s lack of consistent accuracy. But as of today, there are elements happening in the macro environment that have instigated this flip to hawkish. CME is a windsock, remember.
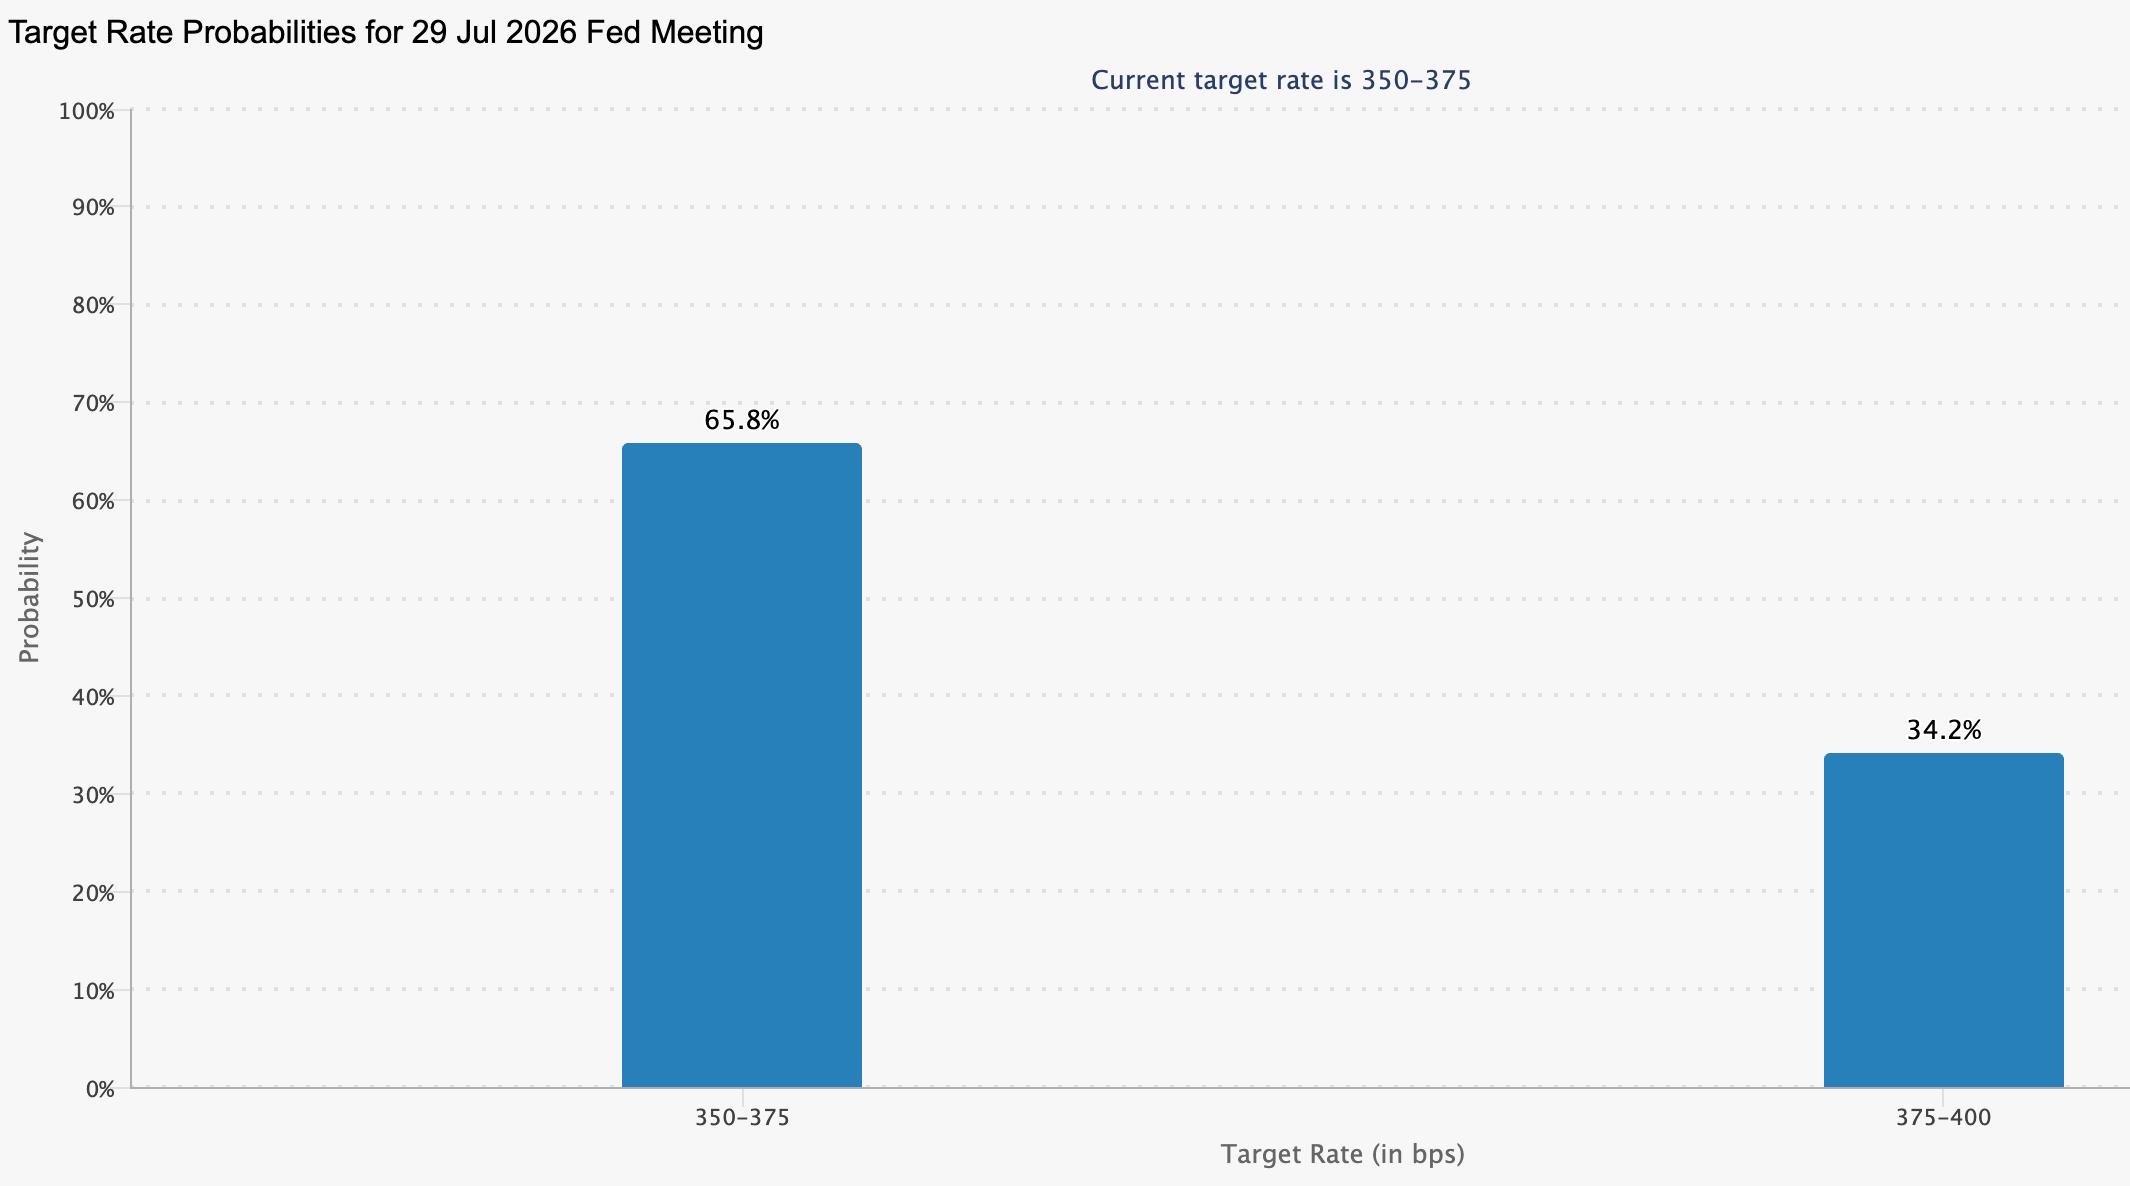
The September meeting is forecast to bring at least one rate hike by 82% of traders.
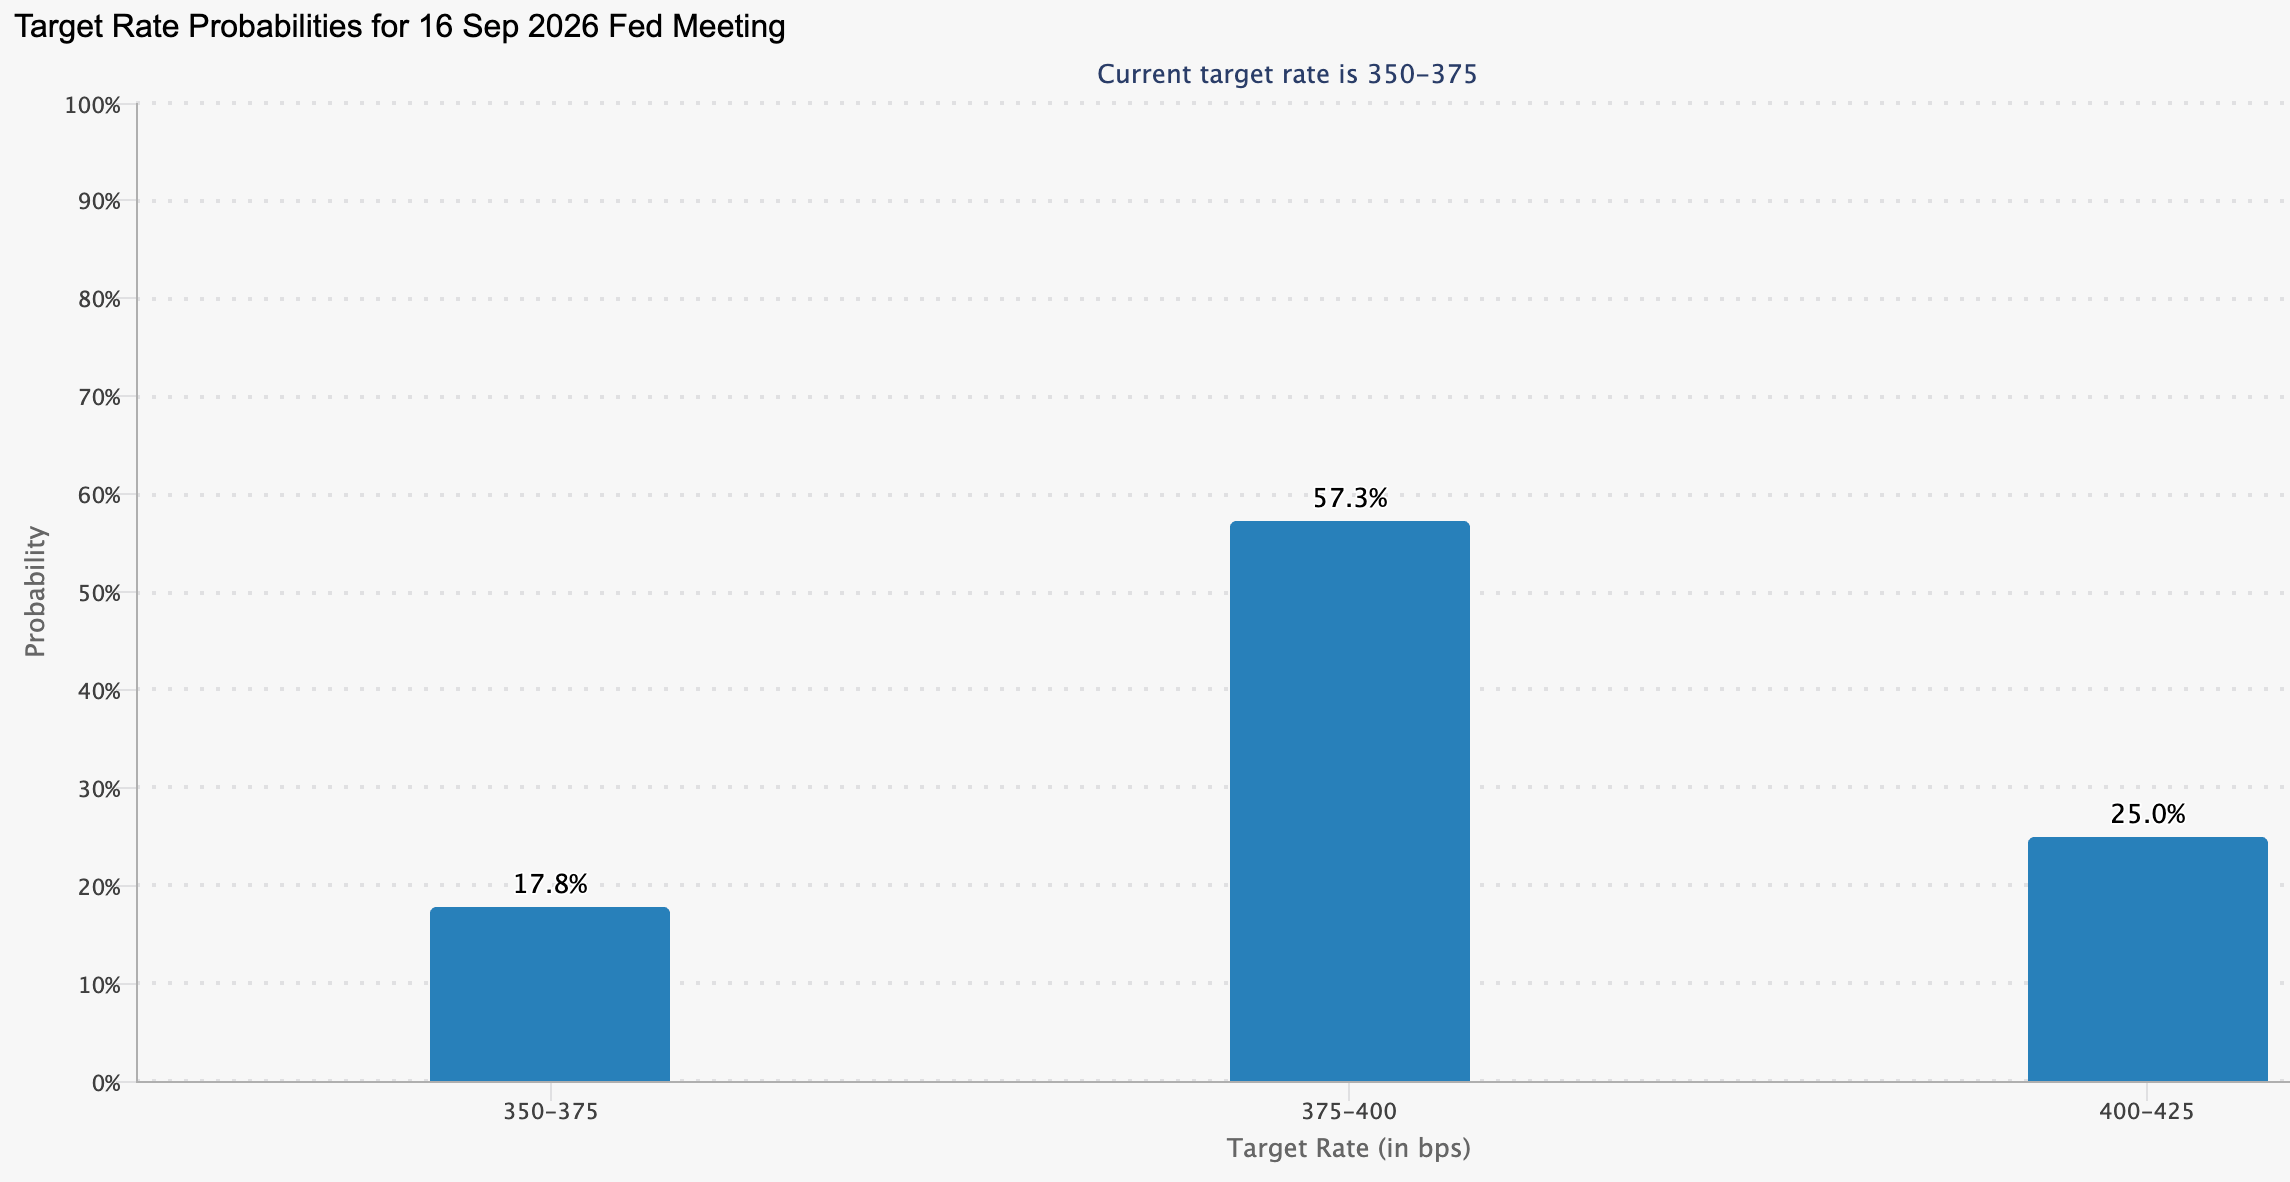
Please reference our discussions about the “new” Warsh-led Fed and its new modus operandi (which I am still working on understanding), its relationship with Bessent at Treasury (all recent Fed heads have been in the hip pocket of the Treasury secretary to one degree or another, IMO), and most importantly, about bank de-regulation that we began a couple weeks ago in NFTRH 923.
Bank deregulation came about last week. See Friday’s public article:
Gold Market Bides Time As Pigs Set Free
2003-2007?
This would be the 2003-2007 inflationary plan. But to follow that plan the US dollar will need to stop bulling and roll over into its primary and mega long-term bear market. That does not appear imminent. But with Warsh having established a sound reputation in the micro-term we’ve known him, and considering the CME alignments above, a rate hold could conceivably instigate a USD decline (and asset market rally).
That is just thinking aloud. I have no idea what they are up to in the immediate-term. I do think I know what they are up to in the longer-term; inflation. By way of the commercial banking industry, ala the 2003-2007 credit bubble. But there is one fly that needs to be removed from the ointment.
USD is currently short-term bullish, as per recent analysis. A 2003-2007 style global inflation trade featuring commodities, precious metals, EM, China, US stocks (which would likely under-perform global in general) is simply not going to get going against a strong USD.
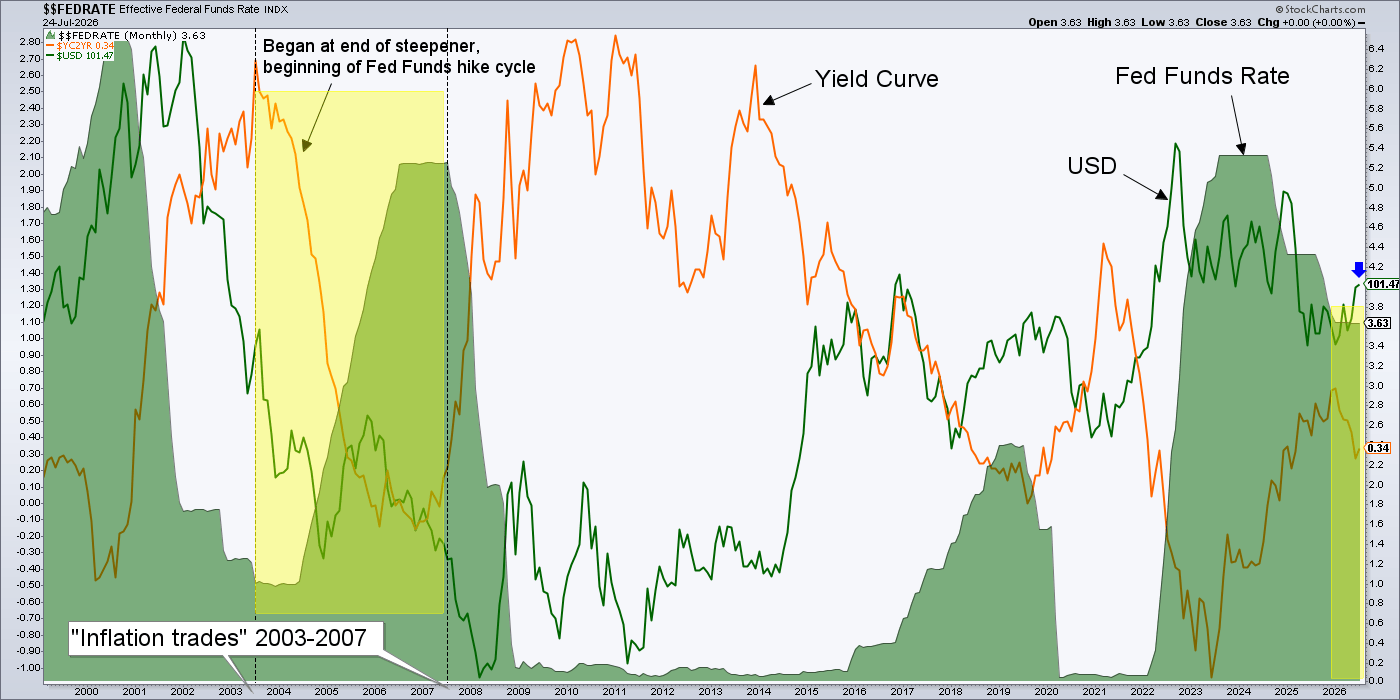
This template shows the Fed flat to strong on the Funds rate (green shaded), and a flattening yield curve (orange) in 2003-2007. It also shows a USD resuming its big decline from the previous major peak (2001) within its mega bear market. The blue arrow shows Uncle Buck not yet getting that memo.
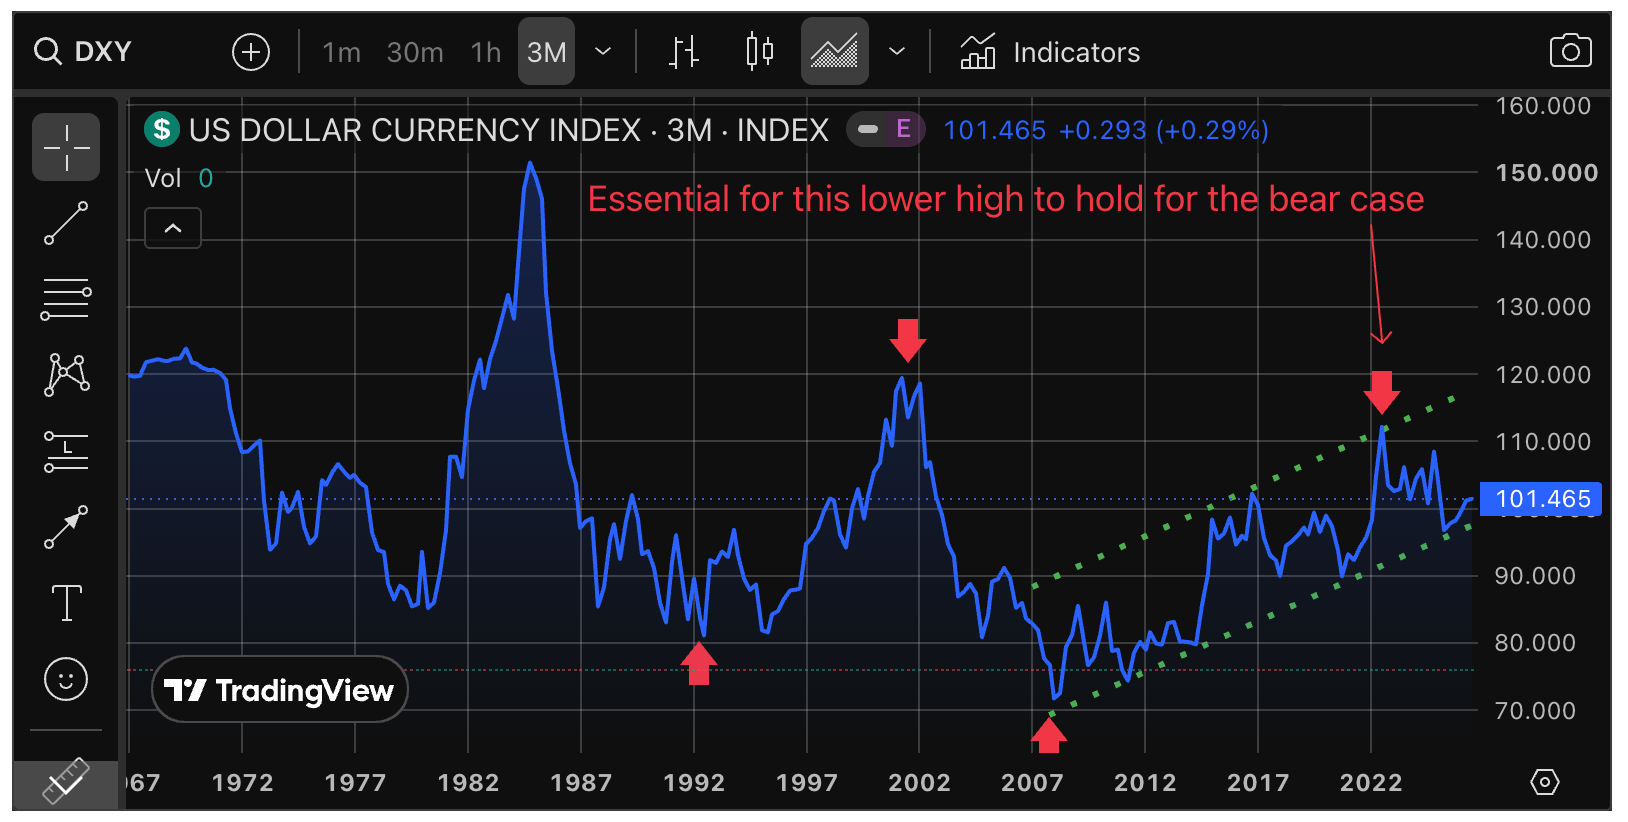
Here again is the very long-term view of the US dollar index (DXY). I don’t have much to add to this chart, other than if USD continues to bull and takes out the 2022 high of 114.78, the 2003-2007 plan goes out the window. At any such time that USD aborts the bull market that began in 2008, the plan very likely slams into place.
Stock Markets
The technicals are not good for SPX (daily chart). Trends are firmly up in a bull market, but it appears SPX made a short-term double top with a lower high on July 15. Then it failed the 50 day moving average and painted RSI and MACD ugly.
I have added Fibonacci grid showing that a 50% or 62% retrace of the rally from the March 30 low would put a hard test on the 200 day moving average. There is also a gap down below at 6618. I am short SPX via SPXS to hedge long positions.

SPX is set up to decline further. Of course, with nefarious forces at work inside the workings of things, it will probably only decline if they want it to decline. Frankly, I see a slight possibility of that, so as to help relieve pressure to raise the Fed Funds rate and/or gain public support for future stimulative actions.

Nasdaq 100 looks almost too obviously (short-term) bearish within this dome. The objective would be a smack at support just below the rising SMA 200. As with SPX, trends are up and it’s a bull market beyond near-term technical vulnerability. I am also short this pig.

The leader, SOX, is under a dome of its own. If it does let go it could be looking at the 62% Fib retrace of the rally at 9978, a tap of the SMA 200 (9122 and rising) or if things get real bad, a smack of support at 8000. But why not see if it can lose the dotted neckline before getting too excited about that?

The SOX > NDX > SPX leadership chain is not standing in the way of further market correction.

US Market Sentiment
- NAAIM had sunk to 84% bullish from 95% bullish even before (7/22) the market cracked at week’s end. They are more nervous now with plenty of downside room should they start to stampede the exits.
- AAII also started looking toward the exits on the 22nd, declining from declining from 45% bulls/33% bears to 30% bulls/42% bears. Ma is really pissed at Pa for his speculation in AI and Rockets and other overvalued areas. This after she slapped him upside the head over his previous Crypto adventurism.
- High Yield Spreads, while depressed on the bigger picture, did spike to end the week. That was a jolt of nerves amid the ongoing complacency. Plenty of headroom for more nervousness.
- VIX is moderately low at 18.57, but is postured for further upside, technically. That upside, if it happens, would obviously come with stock market downside.
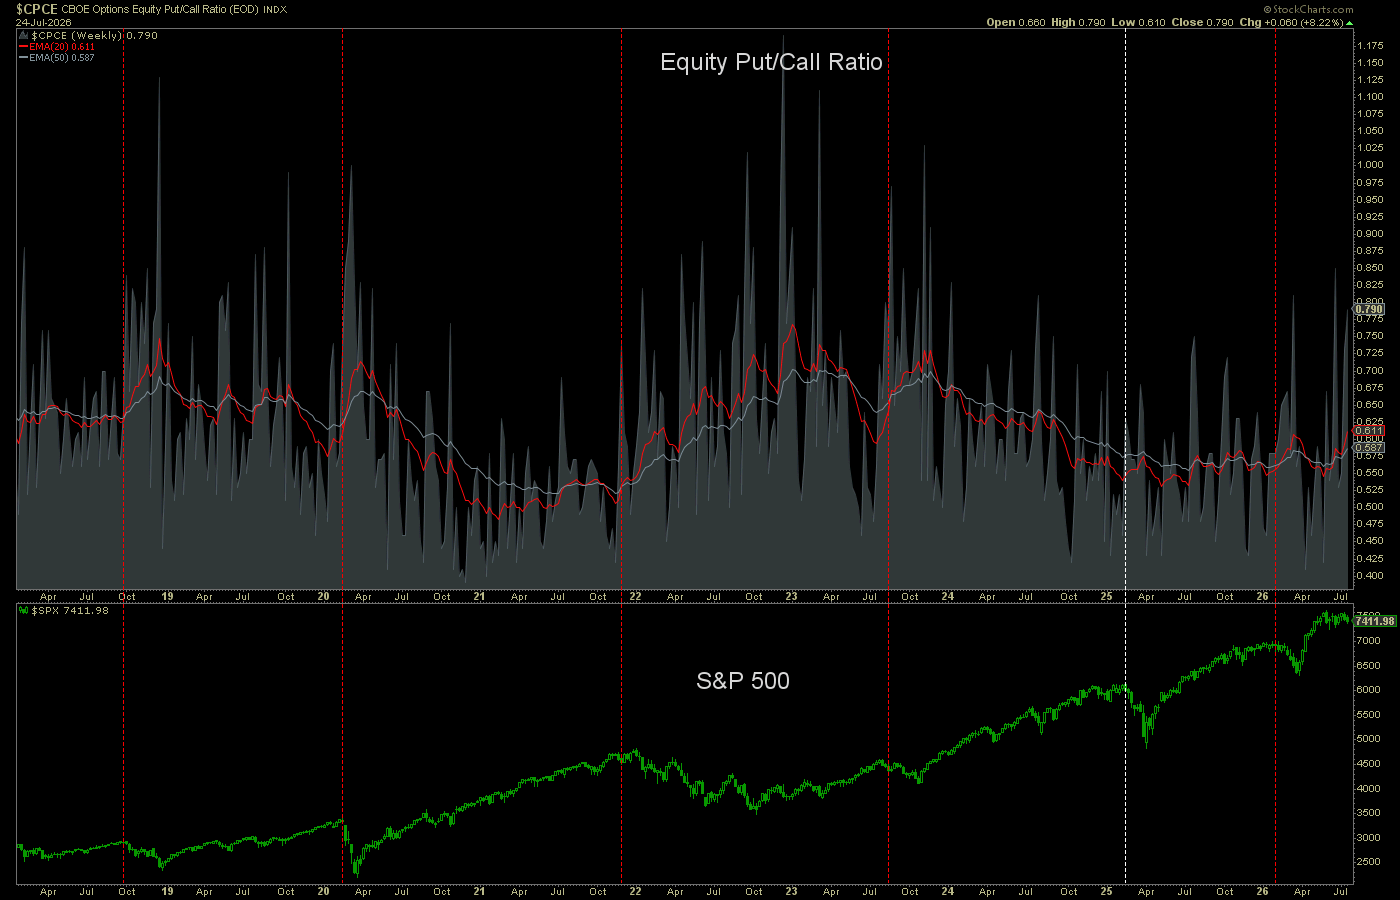
- I just love the chart of the Equity Put/Call ratio. If it turns out to have forecast for us a highly reliable bear signal, you can bet this will be primary in our sentiment toolbox going forward. That upside trigger of the moving averages just needs SPX to crack in order to make it 6 of 7 corrections it will have forecast.
Global Stock Markets
The broken white downtrend line in the ACWX (World, ex-US)/SPY (US) ratio goes back a heck of a lot further than 2023, as shown here. The downtrend in ACWX/SPY and global stocks in general vs. US stocks goes back to 2008. That just happens to be the year that the current bull cycle in USD began (ref. DXY above).
So you can see that it is important to the 2003-2007 global “inflation trade” scenario for USD to weaken. If it does, we’ll expect ACWX/SPY to resume its rise. If it does not, welp?


However, the favored view is that a 2003-2007 style macro will eventually emerge, global stocks will out-perform US stocks and the US dollar is going to soil itself back into its mega long-term bear market. But this will require patience as policymakers portray whatever it is they want us to see in the near-term.
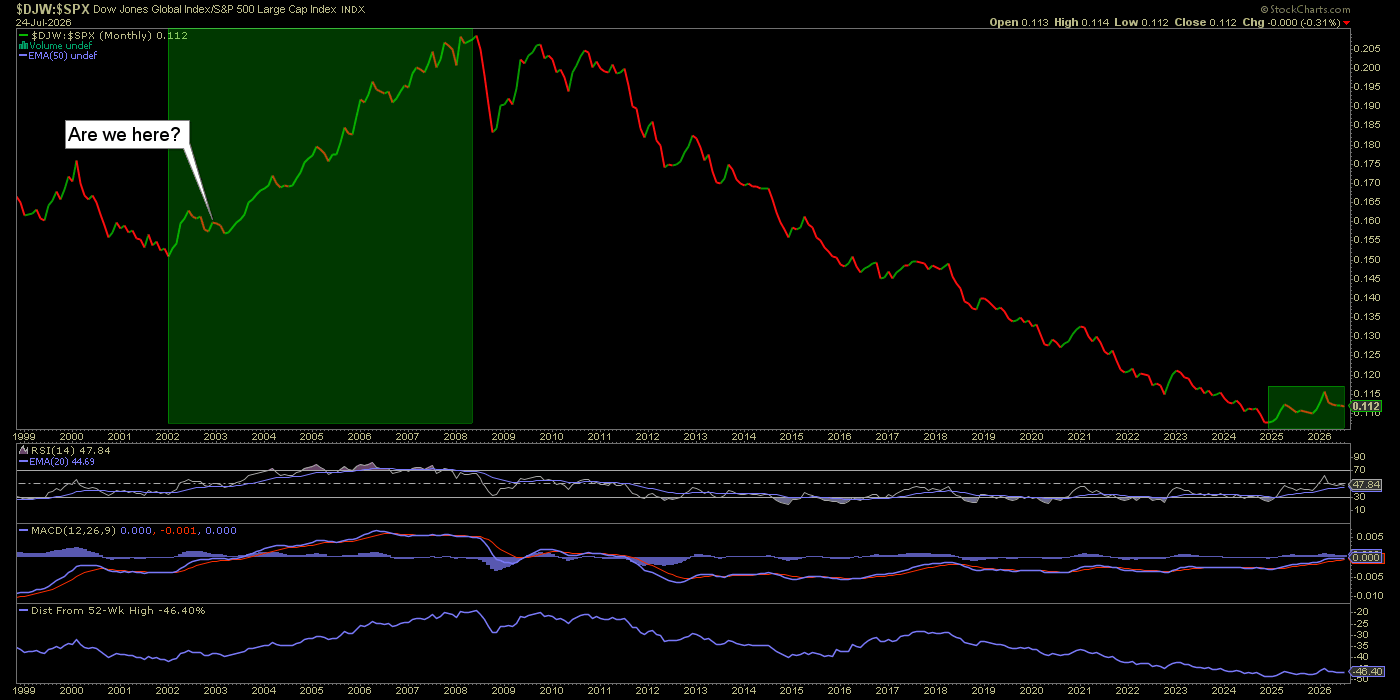
Check it out. ACWX/SPY does not include the history of the 2003-2007 phase, but DJW/SPX does. As you can see, back in 2002 DJW/SPX ended a downtrend and began an uptrend, which persisted into 2008.
If the 2003-2007 plan engages – complete with a bearish USD – it will be a priority to once again look very closely at the global picture for investment. EM/Asia, China, LatAm, etc. and especially resource-rich countries/regions like Canada and Australia. Literally a world of investment opportunity would open up.
The chart asks whether we are at the equivalent of the gateway to the 2003-2007 cycle. The answer is “we very well might be, and if you see the US dollar get torpedoed, we almost certainly will be.”
And if that happens, China, which is experiencing problems of its own presently, would be expected to be a prime candidate for investment, much as it was in 2003-2007 (recall Jim Rogers’ “Ahhm teachin’ mah baby girl Mandarin” jingle from that period).
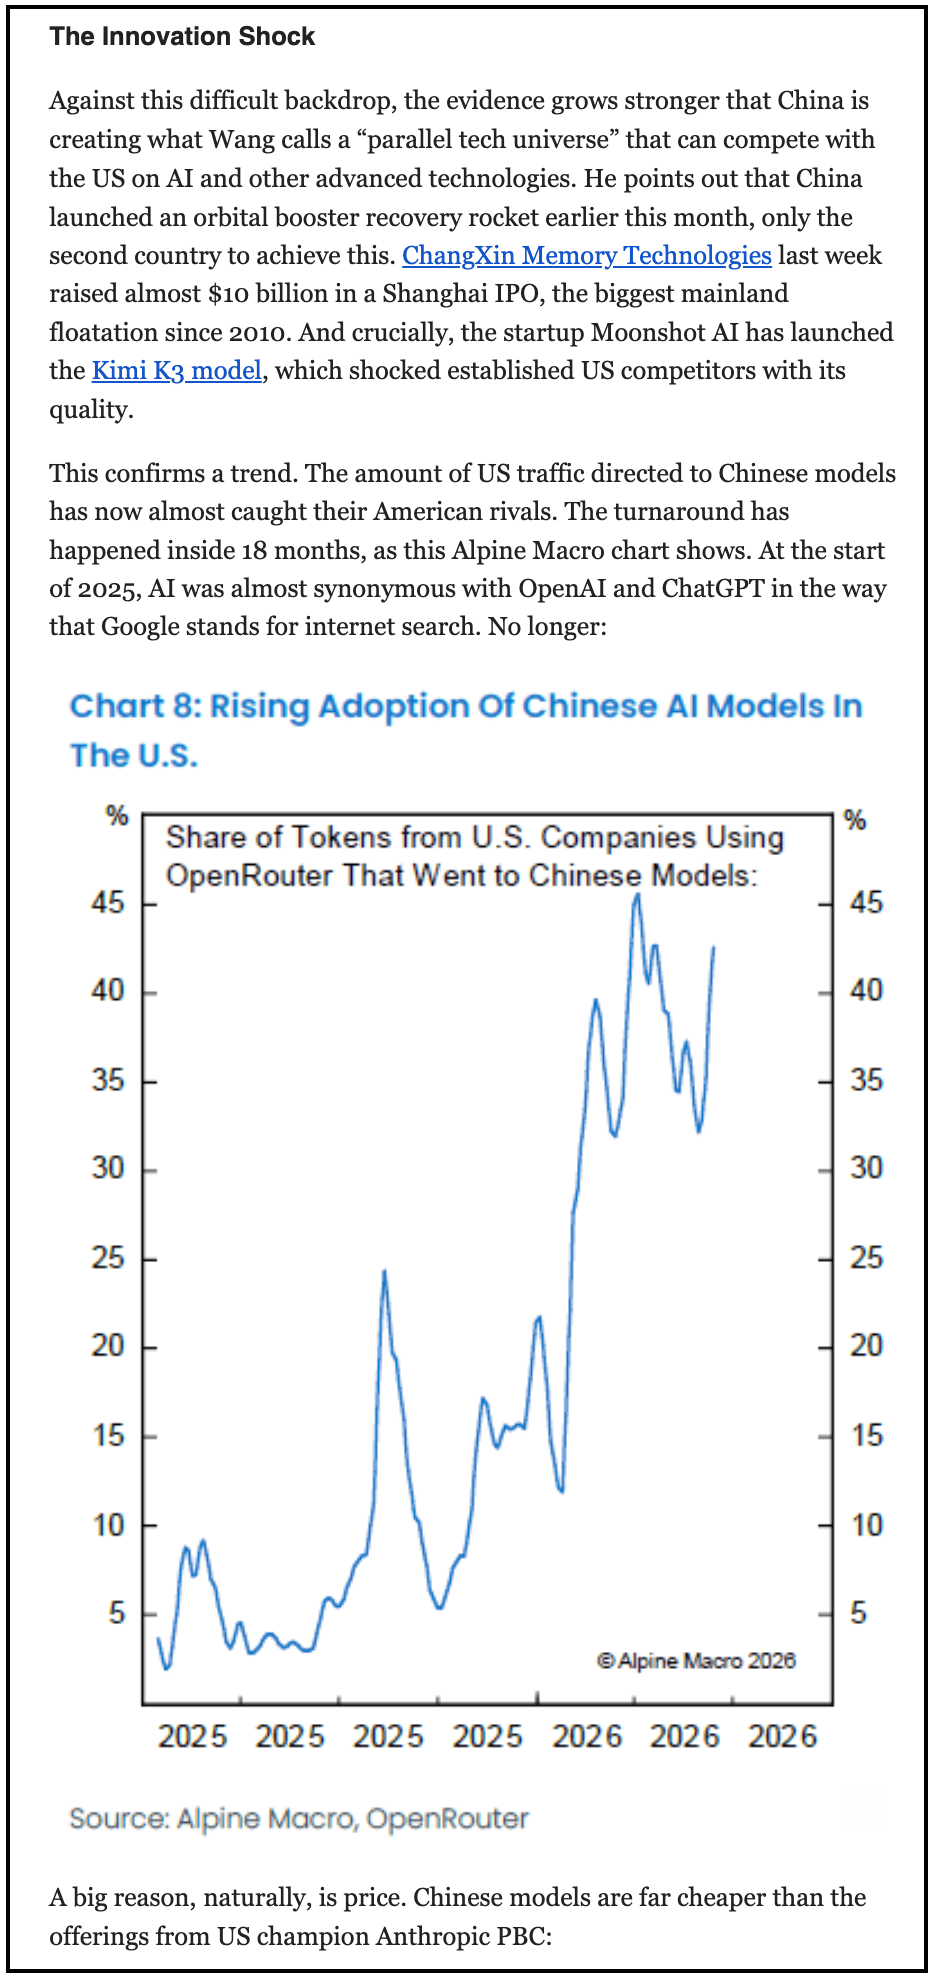
Be that as it may, China would be a prime investment destination. From John Authers (Bloomberg) comes but one rationale for that.
Stonks
The theme for most of 2026 has been rotation, based on market internals and macro gyrations. For example, Semiconductor stocks banged into a full fledged mania as the herds put 2+2 and realized they’d better buy the AI “picks & shovels” rather than the AI model creators, which are rapidly becoming subject to intense competition.
This happened in 1999-2000 as well. I clearly remember thinking ‘no dot.coms for me, I’m in picks ‘n shovels, AKA infrastructure, no problem’. Yes, problem! Optical networking, content management software, etc. eventually got killed. Lessons learned and kept for a lifetime.
Anyway, recently the market internals picked up on this with Semi and herded back into Software, which had been overreacted against in the face of AI obsolescence. I/we bottom fed several software stocks, of which I believe I only still hold DDOG, and added NOW last week as a post-earnings bottom feed.
So, being short to hedge (SPXS, SQQQ & TECS) I have held a few bull stocks like the two noted above along with GOOGL, MSFT, AMZN and RDDT. I also added a preferred Semi in CRDO, which took off and then got clubbed, MRVL and APH, which is about as “infrastructure” as you can get with respect to AI/Semi.
But I have stuck to diversity, and hence Healthcare (Biotech, Medical Device) and Cannabis/Psychedelic. Biotech related items currently held are GILD, BMRN, REGN, QURE, NVO, LLY and AUPH. Medical Device is MDT and IHI. General Healthcare is PACS.
Also, the bank ETFs KRE and KBE are held.
But if the stock market really cracks, most or all of this stuff will get hammered, defensive or not. I am aware of that and though next week is moving week for us (into our downsized home), I’ll be watching as closely as I can as often as I can. FOMC smack dab in the middle of it all? Yes, perfect. And likely, volatile.
Precious Metals
Gold stocks are in the midst of a poor fundamental backdrop. Gold/Oil ratio is back in the tank, real yields are trending up and implied (as opposed to real) confidence remains high. What’s more, politicians in conjunction with the Fed and Treasury, have cooked up a deregulatory banking environment.
None of this is good for the gold miners. But it was not good for them in 2003-2008 either, when they rose 350% or so along with the inflation trades. So the view continues to be that gold miners are nothing special in this environment.
Gold stocks will probably bull, but other commodity/resources items would likely bull better and for better reasons. It is important now to ignore the Siren call (brainwashing) by promoters and understand that if you’re in the sector, you at least know why and to what degree.
GDX (daily) is still trudging along inside the “massive bull wedge” that a promoter hyped us up about weeks ago. There is a bullish RSI divergence in play, and there is still a question in my mind about whether a final volume capitulation will be needed.
In the short-term, GDX is still working the bounce scenario, which is to be expected given the “death cross” of the 50 day average below the 200. Much will depend on the macro, policymakers’ signals for the US dollar and the bond market’s signals (e.g. curve flattener/Golilocks or not) in determining if a better and perhaps major buying opportunity lay ahead.

It’s a tough call because big picture wise, HUI has already tested the top of the 2008 topping structure. Back in January we could have only hoped for such an opportunity. Now it is a matter of whether to get greedy or not, with respect to lower support in the 480 area. This is why it has been recommended for interested non-traders to at least nibble, which I have done.

But again, this is with the caveat of “not special” as the precious metals were in 2025.
Gold would under-perform other commodities if the 2003-2007 blueprint comes to be.
Gold also has a positive RSI divergence that it is trying to bounce from (and a death cross against which to bounce). There is strong resistance overhead and little support below current support, until 3400.

But if gold is to be an under-performer in a 2003-2007 plan, what does that say for the US stock market? It says that as per 2003-2007 (and longer range, per 2000-2011) broad US stocks may bull, but there will be far better places to focus on. Even gold, itself potentially an under-performer.

Silver could indeed have one more plunge in it – again, pending the manipulative forces in play in the short-term – but at some point if the plan noted above is a good one, silver should take back leadership from gold. Silver has retraced nearly 60% of its bull market from 2020.
A final plunge would be fitting, and in my opinion a massive buying opportunity. But silver has done great work since exceeding our upside breakout target on unbridled enthusiasm. I have plucked a couple silver stocks in case we only get the significant buying opportunity that the 2026 low of 54.77 would be seen as in hindsight.

I am not going to chart gold and silver stocks because the TA is generally not good. The sector is in a hard correction. Many seniors are in similar condition to GDX above. The sector death-crossed, became oversold, is bouncing and has not capitulated. It’s a matter of investment faith if you buy for more than a trade.
Favored items include the royalties (RGLD, FNV, TFPM, ELE, VOXR, WPM, etc.) for their lower geopolitical risk and fundamental risk (e.g. Gold/Oil ratio, and other gold ratios amid inflation). Especially those that carry commodity royalties as well as gold (e.g. ELE and to a lesser degree, FNV).
Also, precious and non-precious metal/mineral exploration stocks, which do not have the cost implications of active miners in an inflationary environment. AE.V/AMEGF (Cu & Au), TLO.TO/TLOFF (Ni & Cu), and the multi-metallic MMG.V/MMNGF are currently held. On watch are items like SGD.TO/SNWGF, CTGO, DC and SKE.
As for the miners, and given the macro caveats noted above, my priorities are AEM, AGI, EQX, CDE and a few others. Currently held gold/silver stocks are RGLD, ELE, HL, RIO.TO/RIOFF and ABRA.V/ABBRF.
Commodities & Resources
Like the precious metals, aside from war driven oil, the sector is pretty much in ongoing correction or bombed out. Favored items continue to be “critical” minerals/materials (to varying degrees):
- Copper: Cu is bullish, in a sideways correction of sorts but solidly trending up. Copper miners generally in an ongoing but not severe correction. Holding COPX, FCX and SCCO at this time.
- Nickel: Ni is early in a new uptrend off of a long correction. Favored stock is the still speculative TLO.TO, and will watch for other more mature items.
- Uranium: u3o8 is in a sideways correction for all of 2026. Supply/demand is positive and should assert in due time. Holding CCJ and NXE at this time.
- Lithium: Li price is in correction after making a new cycle high in May. Holding ELVR, which just broke below its SMA 200 and will not get a long leash. Others on watch are ALB, SQM, SLI, LAC.
- Rare Earth: We started watching MP back in 2023 for the exact reason that played out in 2025; the strategic aspect of US production and processing of REE. But the government is involved and the fallout from the hype is real. It’s similar to my hatred of Intel (on which I should be short). State-sponsored corporate socialism. This year my watch list favors the littler fellers like IDR, CRML, TMC, etc. But MP and LYSDY are also on watch.
- Agricultural: The Ags are not something I want to play directly. But I do have an eye on MOS and former holding IPI. Especially MOS at this point. NTR is the other play.
- Oil/Gas/Energy: Look, I am not getting involved with the damn war because I am trying to stay away from Trump’s big mouth. Woo hoo, oil is bullish because Trump can’t (or won’t) extricate himself from the stupid and dangerous war he allowed himself to get pulled into. No positioning. Gas plays AR and EQT on watch.
Generally, the commodity complex would eventually follow the Silver/Gold ratio and out-perform if we are at all on-base with the 2003-2007 analog. It is what triggered us to get bullish (on precious metals and critical/strategic commodities) before the masses in 2025 and it must abort this downtrend before a sustainable bullish view can be held for commodities/resources/inflation trades in 2026. Period.

Portfolios
Gold is long-term risk management & monetary value/stability in a balanced portfolio.
“Savings” Account
Cash/equiv are 76%, but this includes three leveraged index short positions. Considering the mix of sectors held, it’s sitting quite defensive.
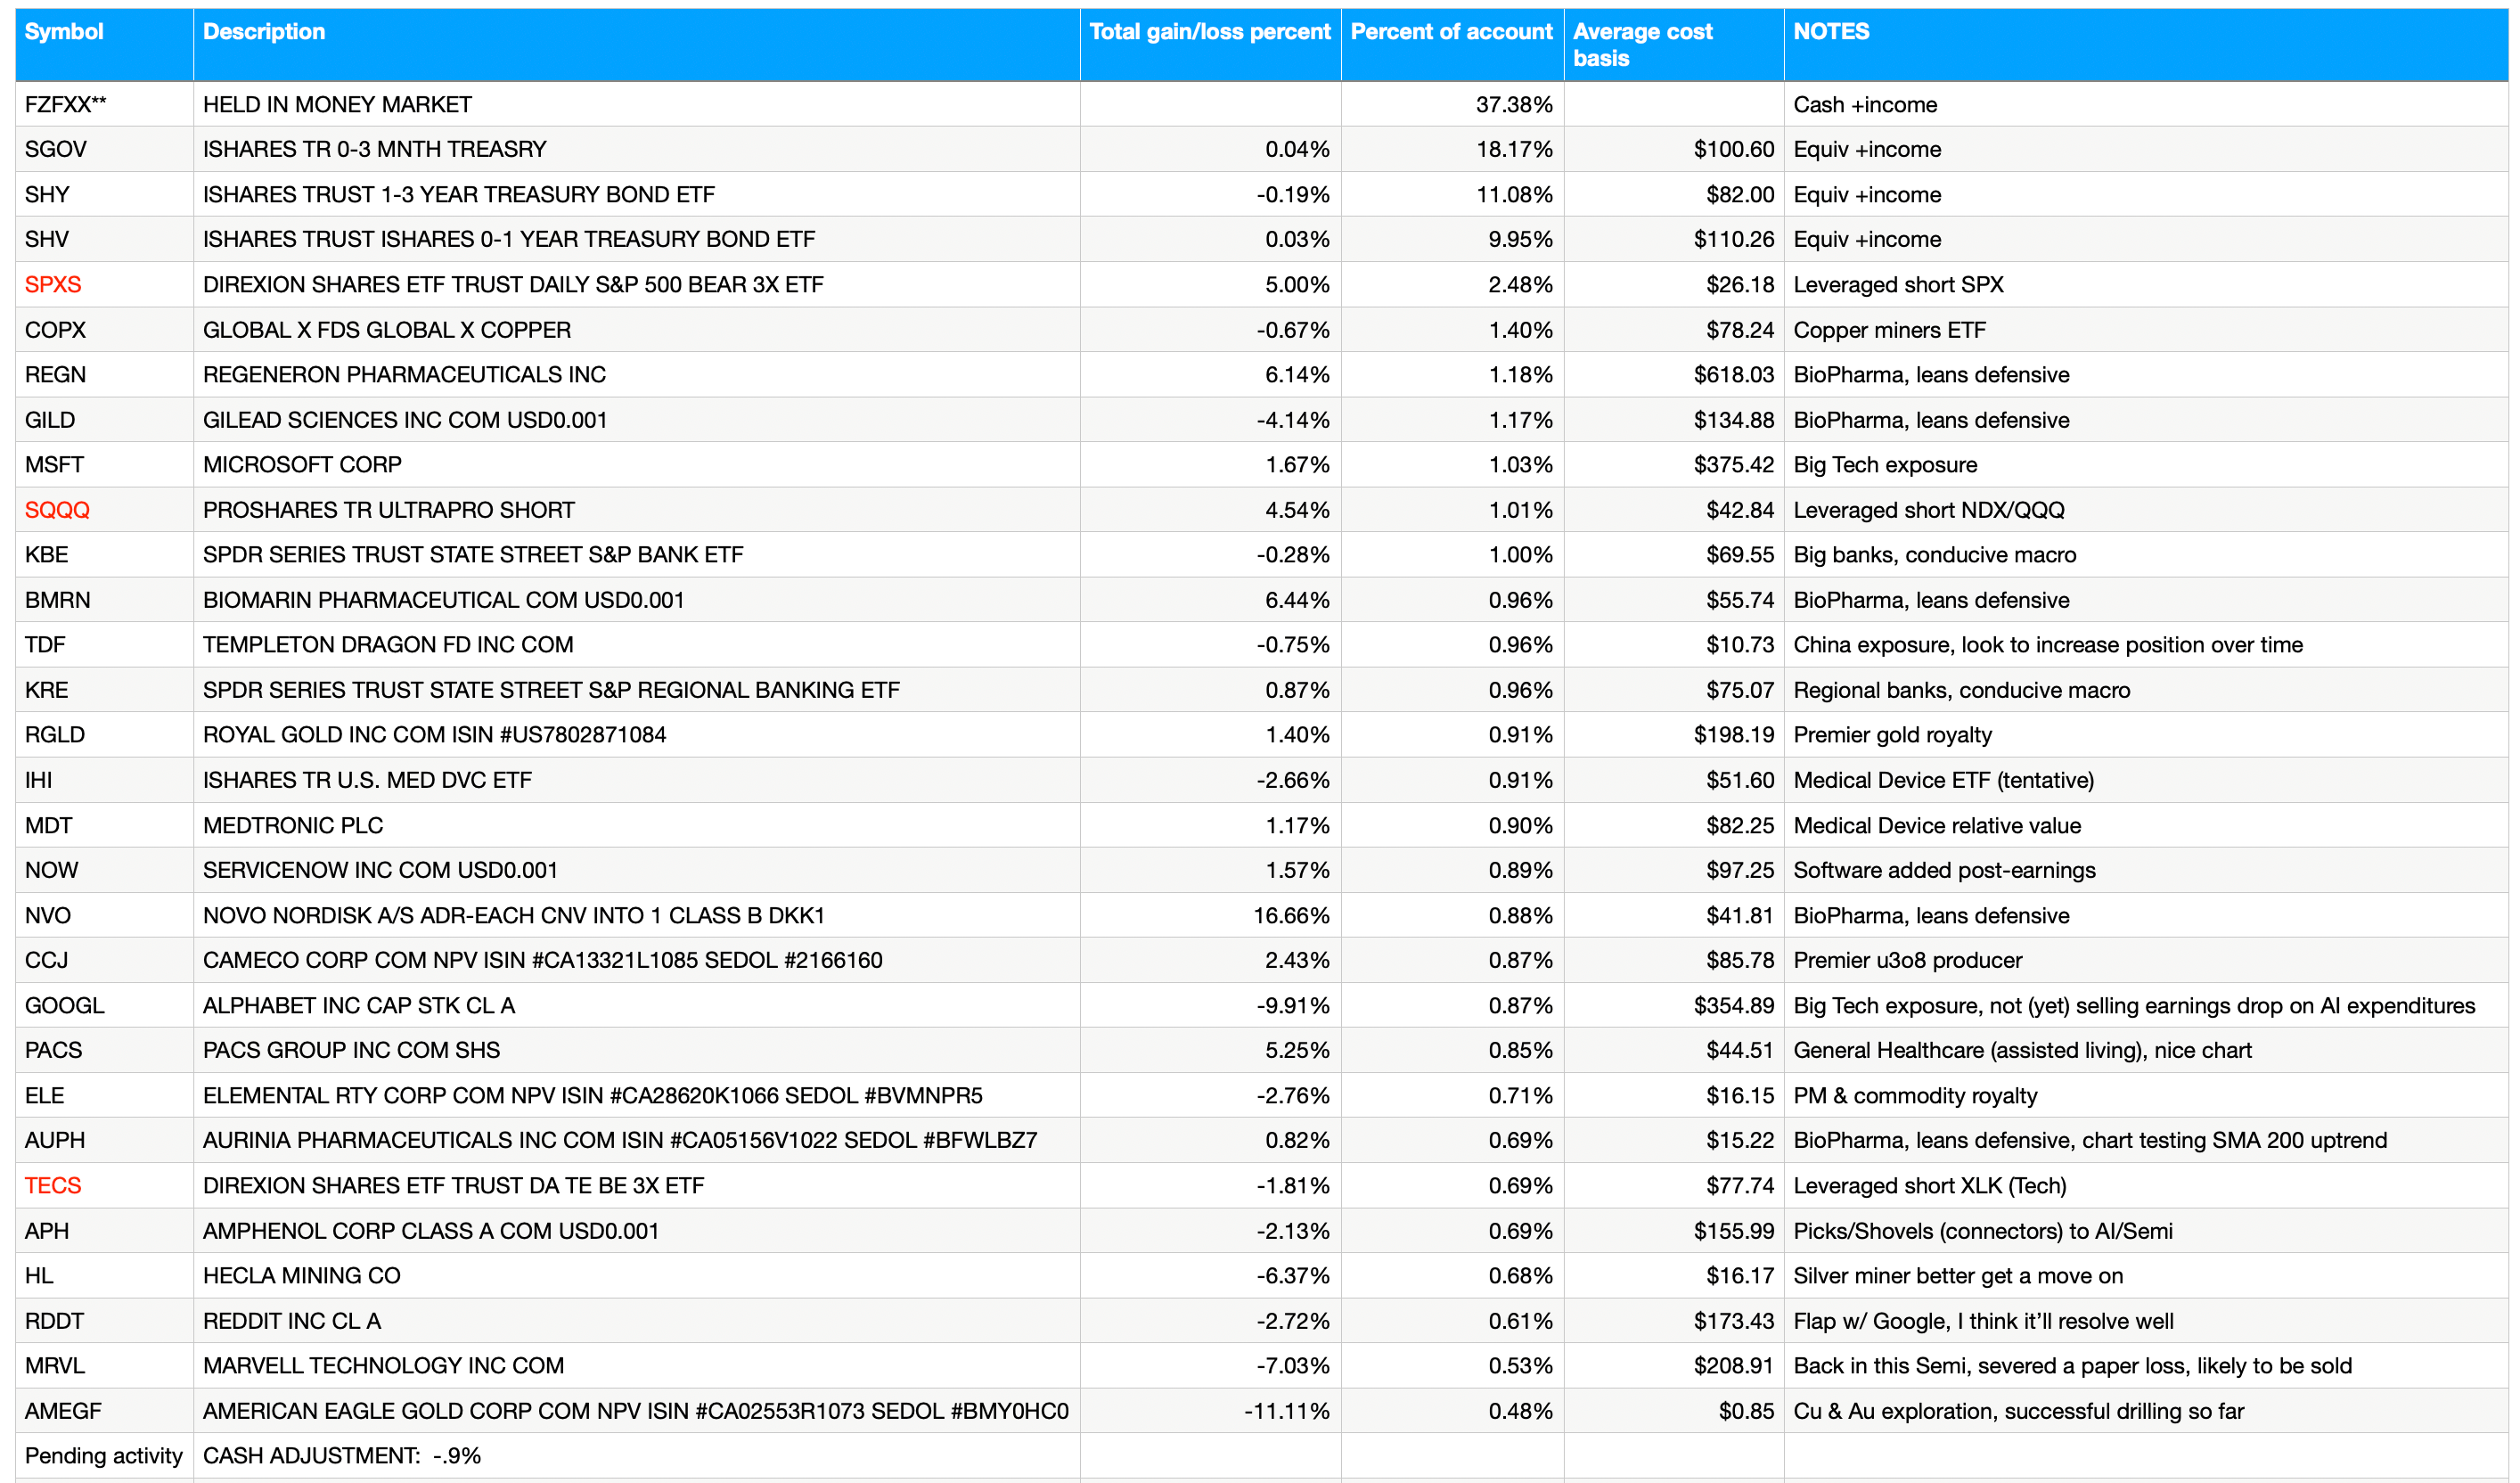
The “Savings” account will vary in its positioning. At times when I am confident of bullish markets it will hold positions, while remaining primarily a cash/equivalents account. At times I am not, it will not substantially hold much beyond cash/equivalents.
Trading Account
No positions
Roth IRA (non-taxable, no contributions)
The 1yr chart is flashing some ugly, but as noted last week I am not going to sweat that. I am going to play defense and take it day-to-day, week-to-week through this volatile period before the Fed goes on vacation into its September meeting. I will do whatever it takes to defend noted support and worry about new upside when appropriate.

Cash/equiv are 75%. But as with the above, this includes three leveraged index short positions. This group is also diverse, but does include a higher level of speculation than the ‘savings’ account.
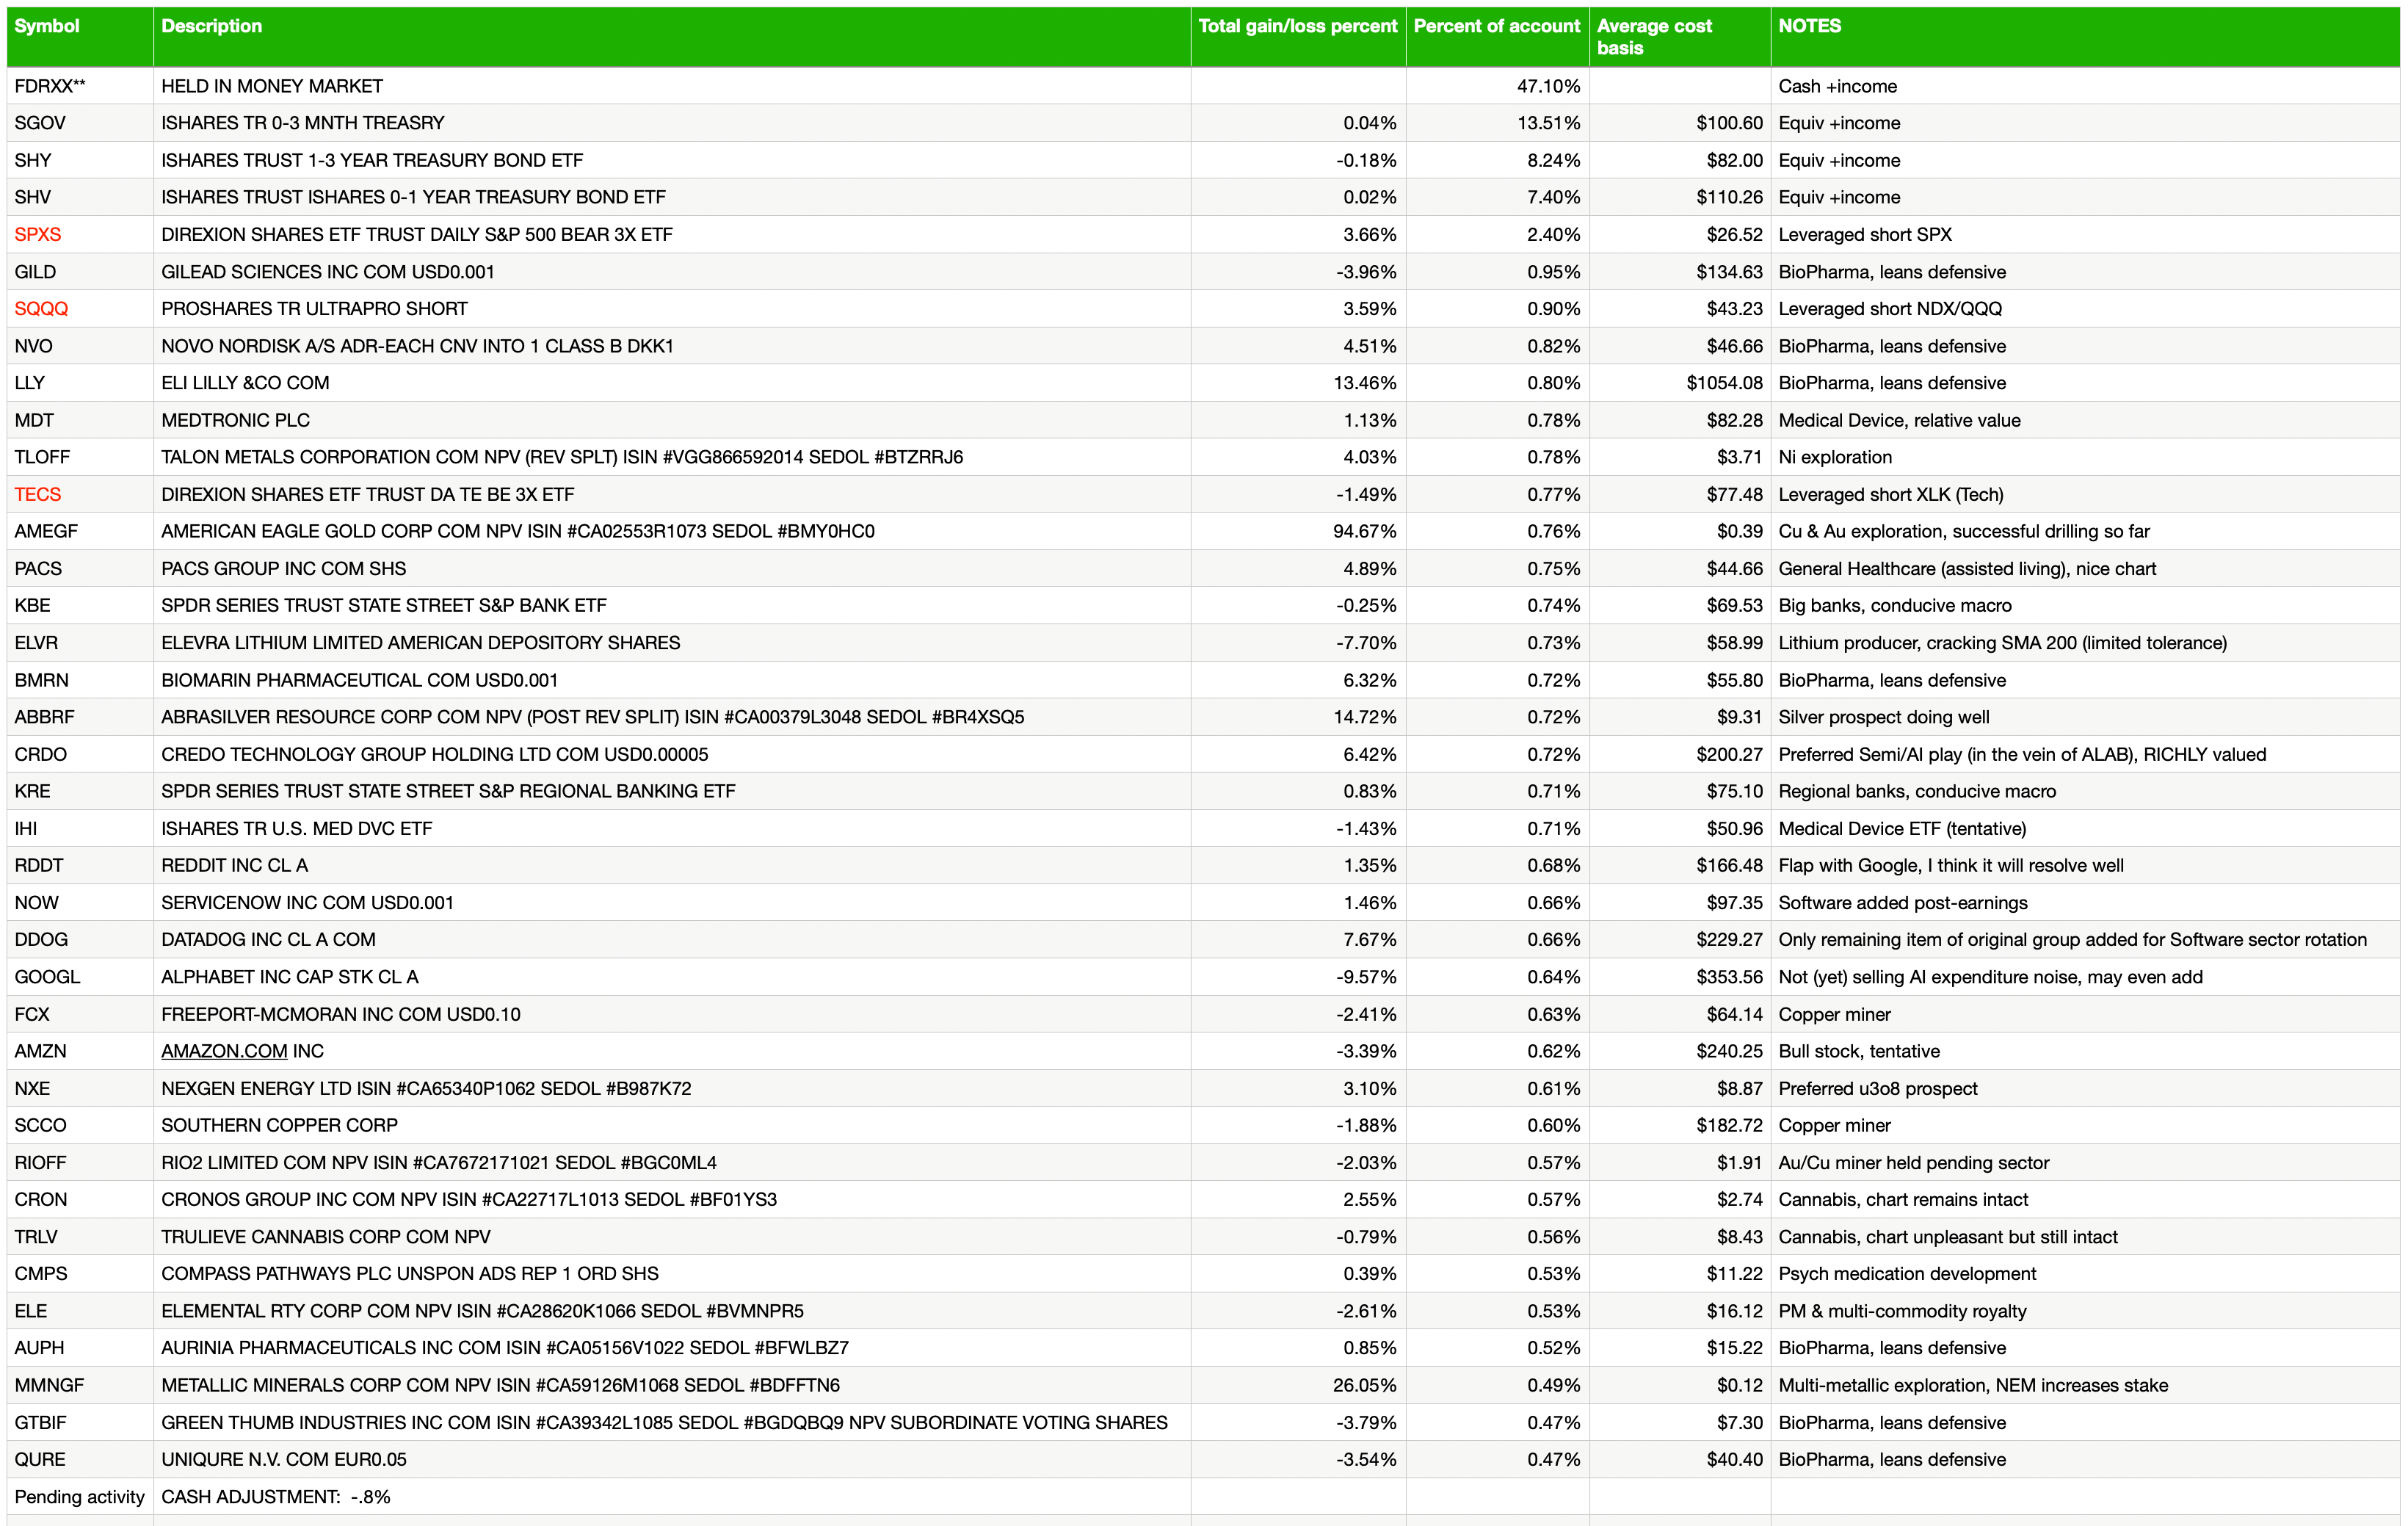
Cash & income-generating Treasury bonds are at levels that are right for me and my real-world situation. Your situation is different. Cash will be adjusted as needed.
Refer to the In-Week Notes under the NFTRH Premium menu at nftrh.com for market talk and occasional trading info, if interested. Also, you can follow on X @NFTRHgt for notice of updates.
NFTRH is not to be distributed to third parties without prior written consent
Notes From the Rabbit Hole (NFTRH) is a weekly market report in which we provide analysis on financial markets. We make every effort to provide accurate and high quality content, but this analysis ultimately represents our opinions and these opinions are provided without warranty or guarantee of any kind. See full terms & conditions of service under the ‘About’ heading in the main menu.

Morning Gary.
Small detail. On the Canadian exchanges Rio2 has graduated from the dot vee to the dot tee oh (rio.to)
Right you are, sir! Thank you for the heads up. Fixing it now.