
It’s something I’ve mentioned a lot in recent months. The price increases due to war and global trade tariffs/wars are not the product of inflation. Yet the Federal Reserve has been acting as if they are. That’s an interesting word, “acting”.
Prices are rising, in large part due to decisions made by politicians (fiscal policy), not monetary authorities. I think that is important because monetary authorities are reacting against it through monetary means. As if limiting credit and liquidity * will help a situation born of geopolitics.
All Trump has to do is make one of his insane comments about annihilating Iran, all the Houthis have to do is bomb a Saudi refinery, all Iran has to do is take out some tankers, all China has to do is this, Russia that and Ukraine the other thing. Voila, price spikes!
Captain Obvious: “It’s the damn shooting war. But it is also the trade war.”
Meanwhile, we have noted that gold has held up better than you’d expect with the USD so strong at the behest of hawkish policy and very elevated “real” yields. But what have we here? We have real yields rolling over. Not only that, the real 10yr yield is finally rolling over in line with what we have noted all along; that the Breakeven Inflation Rate was flat.
In other words, my interpretation is and has been that it was not monetary, regardless of prices. Monetarily, it’s a disinflationary environment. Or at least a flat environment.
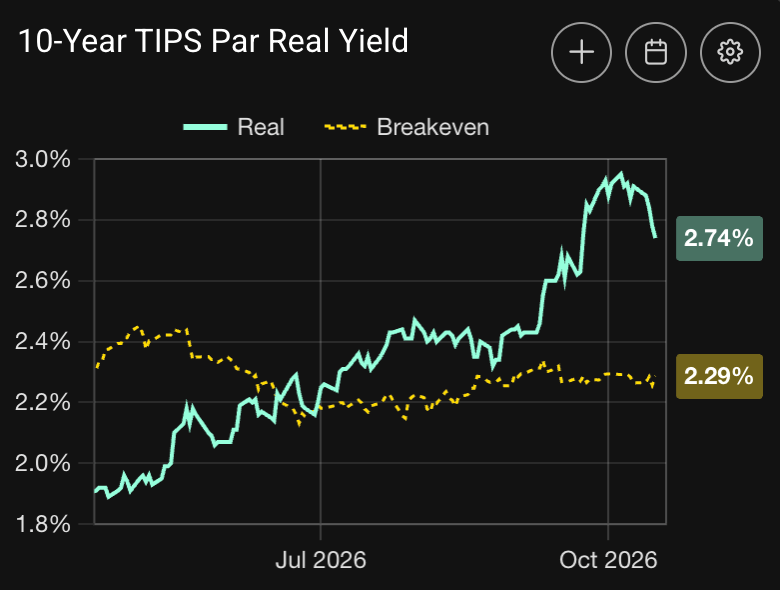
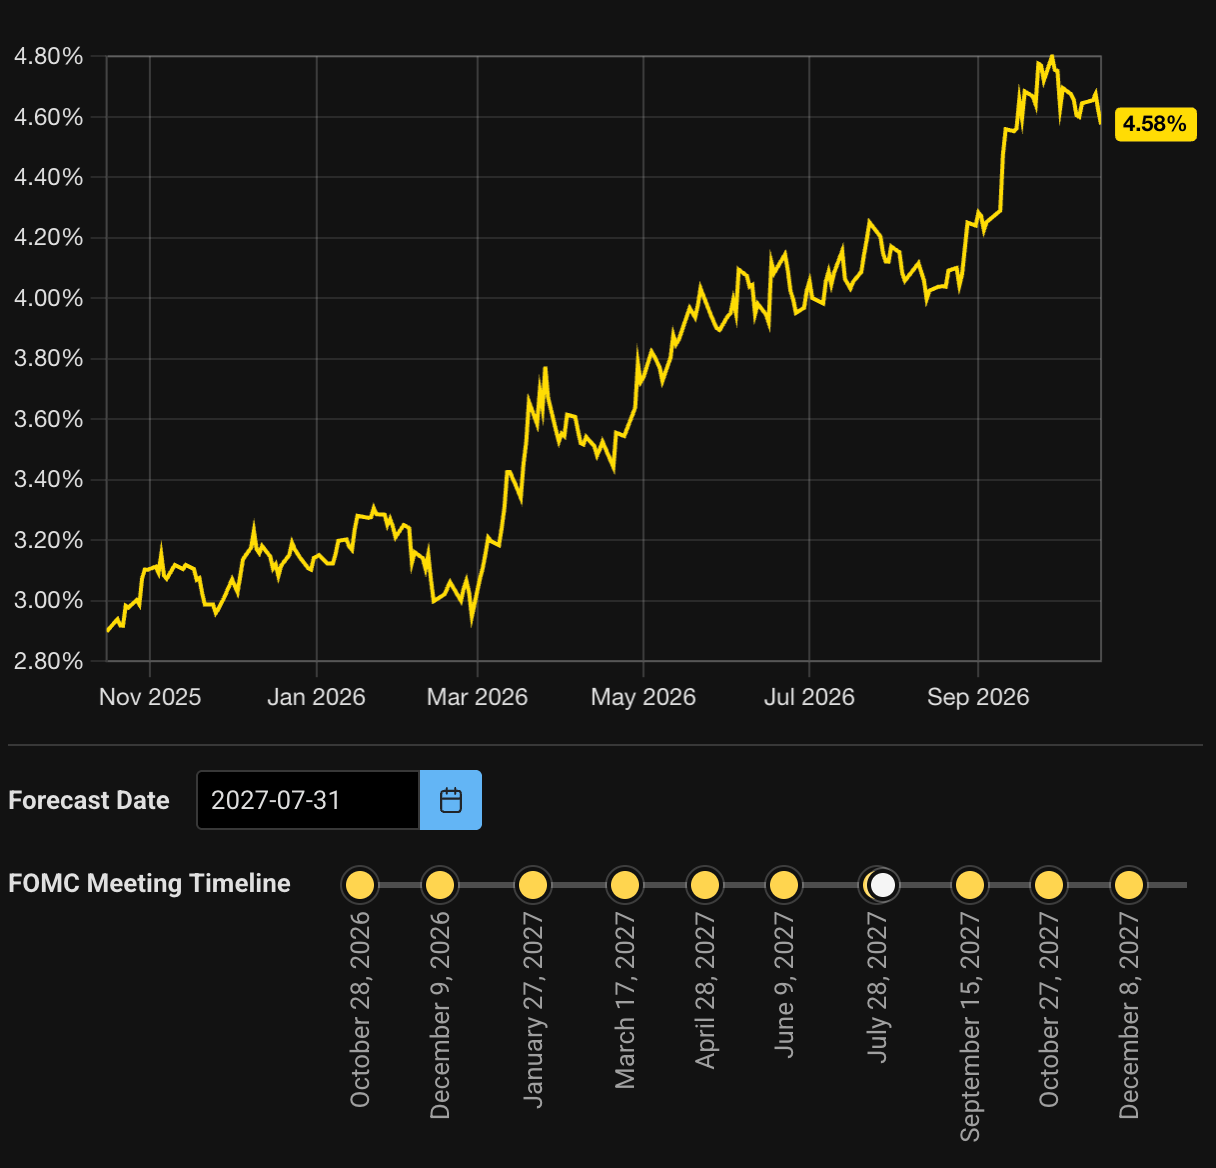
If the real yield continues to roll over, the US dollar will start losing underpinnings of that heretofore bullish fundamental, and the Fed will start to weaken its hawk stance. Below is the anticipated Fed Funds rate over time. Obviously, it is always wrong, by definition. If it were right all the time it would be a flat horizontal line.
So it’s of little more use than the windsock we note the CME Fed Funds traders to be. Now, if this also rolls over a lot of people are going to be caught on the USD-bullish side and the gold-bearish side. Meanwhile, the real price drivers, shooting and trade wars, keep shorter-term volatility in play. But looking beyond that, if there is a “beyond that”, gold should eventually grind out a resumption of its leadership in the big picture macro and the US dollar should enter a bearish phase.
* Let’s for a moment set aside the fact that Bessent is in the bond market at the same time attempting to open the credit spigot on the long end of the bond market.
