

Summary
A brief summary of the work done in this week’s report and in the updates and reports leading up to this point. Please read the detailed report for the complete picture. There are many granular details that cannot be summarized so briefly.
Precious Metals (bull market)
Sector in longer-term bottoming mode but no sign of larger correction end. Risk (downside) /Reward (upside) becoming quite good. Bounce/rally potential here. Eventually, gold should lead the next inflation phase after Fed finishes pretending to be hawkish.
US Stock Market (bull market)
Rotate, baby. Semi is manic. The algos appear to be roving internally and playing the laggards. We’re staying in touch with that process. Risk of correction is, in my opinion, high as market liquidity weakens.
Global Stocks (bull market)
Still poised to continue out-performing US, which calls into question the US dollar rally as likely terminal (point ‘C’?). But if US takes a liquidity-driven correction, so too should global.
L/T US Treasury Bonds (bear market)
Bonds finally being driven into the interim rally we’ve expected for so long. TLT breaks upward from its pattern amid the disinflationary implications of Goldilocks and a hawkish Fed. [unchanged]
Commodities/Resources (bull market)
Not time yet to position with any conviction, in my opinion, as the Fed plays hawk and market liquidity is constrained.
US Dollar (cyclical bear market, L/T still a technical bull market)
USD is well on its way to or toward ‘C’ of an A-B-C rally. This is within a cyclical bear, itself within a still intact major bull market, technically.
Market Rotation ‘On’
While we have weighed the prospects of the broad market experiencing Goldilocks, going bearish and/or rotating internally, the main theme has been for diminished inflation expectations. By extension, that would calm elevated Treasury bond yields and favor non-‘inflation trade’ sectors like Software, Biotech/Healthcare and to varying degrees, defensives like Consumer Staples.
Amid easing inflation tensions (as indicated by Treasury bonds rising and yield curves easing) precious metals got a pop and Semiconductors took a drop.
The leading Semi sector took a hit within its intact uptrends and NDX and SPX are in small Diamond consolidation patterns that I would not be surprised to see resolve bearish for moderate corrections. Goldilocks or correction, I don’t think Warsh/Bessent much care as long as it drives down inflation anxiety so they can prepare the next inflation. A game of misdirection they play.
Precious Metals – Gold Stocks
But gold stocks? Well, let’s remember that while they often get painted with the ‘inflation trade’ brush, they are not that. Gold and gold stocks often lead inflation trades by bottoming first and scouting future inflation by keeping an eye on monetary and fiscal policymakers as they shed their hawk costumes and ready the next phase of inflation.
As noted in an NFTRH+ update on Thursday:
Risk/Reward is distinctly back with the precious metals vs. the stock market. And that is on plan with the Gold/SPX (GLD/SPY) ratio, which is now testing our target at the shaded box.
That does not mean that the correction is over or that gold/gold stocks have to bottom vs. the broad SPX immediately. But Risk/Reward (risk of significant downside is now much less than the potential significant upside reward) is the kind of situation you want on your side because even if the timing is off, the risk should eventually clear and open up a favorable situation.
Per the portfolios below, I ended the week with the following gold/silver stock positions:
AEM, KGC, HL, ABBRF, AGI, RGLD, VOXR & ALKEF
I decided to curb my enthusiasm at those holdings, but am ogling former holdings CDE, EQX, TFPM, ELE, SKE, DC, CTGO, MAIFF, etc. I also tucked a small hedge (DUST) in there, which could be gone on Monday or be held/increased if things get rough again and a good (at least interim) low is not imminent.
With the Gold/SPX ratio in range of an anticipated low, what I call a “macro fundamental” flashes positive risk/reward. Ref. Friday’s public article.
Gold/Oil (GLD/USO) is what I call a “sector fundamental” and the gold mining product looks to be bottoming and preparing for an upturn vs. gold mining cost driver, crude oil. My concern has been about Q2 reporting in late July/early August. But it is entirely possible that the gold stock correction is already factoring that, especially since some larger miners offer (AISC) cost guidance ahead of time.

HUI (daily) remains in the wedge (correction) and will attempt to bounce from support. And no I give no credit to the promoter we discussed last week cheering on gold bugs as if they are children with respect to a similar wedge on GDX. That cheering came at about an 18%-20% higher level. As you can probably tell, it disgusted me. This is not a cartoon or a game show. It is serious business.
I think that when gold stocks do make a final low – if it’s not in already – having been cold, calculating and defensive will have paid off handsomely. No need for clown shows and hype fests.

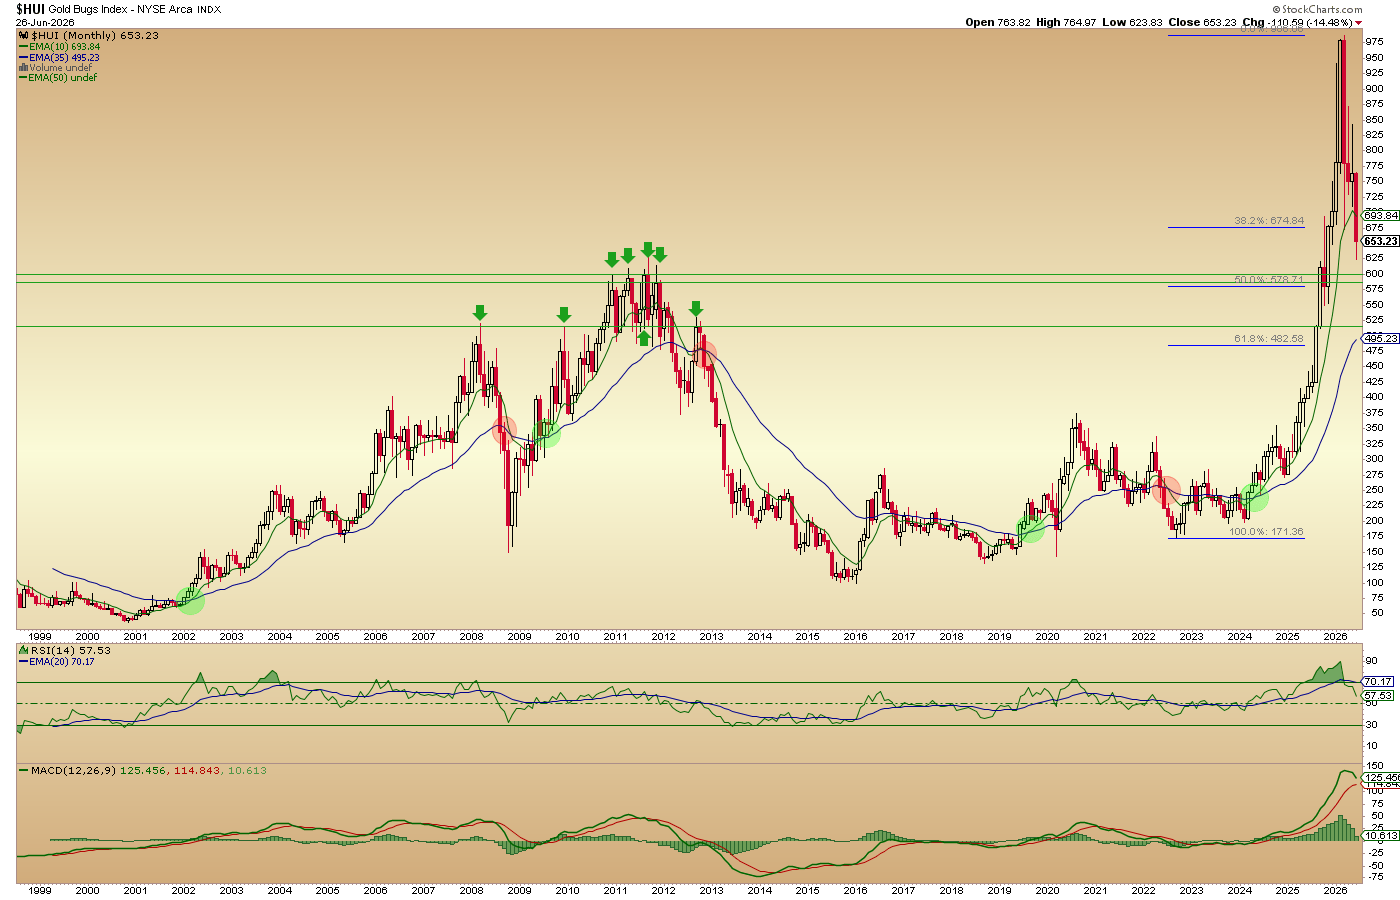
HUI monthly has barely tickled support at the top of the 2010-2011 topping structure. It may never take a deeper test. But we are only managing a potential for a bounce right now and not calling an end to the correction (though we are calling a vastly improved risk/reward profile at current levels).
Gold and silver are still technically vulnerable, per their daily charts. As with the miners, they can bounce, rally or even end the correction. But nothing has been accomplished yet from a technical standpoint.
Likewise, the Silver/Gold ratio is still still in breakdown mode, technically. This need not impair gold and theoretically should not impair quality gold stocks. But all too often, it does because silver mania, or shall we say silver enthusiasm, often fuels precious metals rallies.
This, along with rallying Treasury bonds, is a beautiful picture of Warsh/Bessent at work under the hood, rigging the macro “just right”.

So again, let’s tap the breaks on precious metals enthusiasm. All we’ve got going so far is a vastly improved risk/reward situation and the potential for an oversold sector bounce/rally. It doesn’t mean an end to the correction cannot develop here. But it also doesn’t mean it necessarily will end either.
Any further bouncing, if applicable, should be viewed as just that until we get some technical confirmation and further fundamental confirmation (beyond risk/reward). But I do think that last week’s lows were a time to try a trade and/or even start to reestablish positions for the longer-term for non-traders. For investors, it could be a process of slowly and methodically buying the pullbacks and wipe-outs from here over time.
Macro
A hybrid “macro/sector fundamental” for gold stocks is the Gold/RINF (inflation expectations) ratio. HUI (yellow) leveraged the Gold/RINF ratio as it should have, during the 2025 rally.
Here we again pound the table on this: Gold miners leverage gold’s counter-cyclicality and the disinflationary winds that blow during a counter-cycle (with gold rising vs. mining cost inputs and inflation signals). Since modern economies are built on inflationary policy, the miners NEGATIVELY leverage cyclical inflation. As always, I would tune out anyone insisting you buy gold stocks for inflation protection. They are out there.
The interesting thing here is that while gold stocks are 47% higher than [gold as adjusted by the ‘inflation expectations’ gauge] from the rough start of the 2025 rally, each has declined about 50% (+/-) from the February highs. HUI has done the logical thing since inflation fears started to become a renewed issue (in terms of gold).

Now think about Warsh, with a little Bessent on his shoulder whispering sweet disinflationary nothings in his ear, and think about the current macro. I believe this is a phase, whether a Goldilocks phase or simply disinflationary with liquidity problems, prior to the next inflationary operations.
This phase is brought on by tough new Fed hawk-talk, driving yield curves down into flattening posture. If they are going to bring future inflation, they have to have something to inflate against. And it ain’t inflation fears, I’ll tell you that. They will not bring more inflation to an already inflation-saturated situation. They need to “rescue” us from the threat of declining prices, especially in stocks. Or at least be given license by the gentle disinflation of a Goldilocks phase. In short, they need to sanitize the current inflation to pave the way for those in the future.
I believe it is bullshit. A psy-op of sorts that CME traders, other humans and machines alike seem to buy every time. Maybe that is the point. The market must be pounded into obedient submission prior to the next inflationary operation. So why not simply obey and get it over with?
That may well be the coding the algos go by: fed-speak-hawk = rotate internally (away from targeted and vulnerable areas like inflation trades). It’s like a game of cat and mouse as the yield curve flattens and the machines scurry to align with interim market internals.

I have little doubt that Bessent and Warsh plan to get back on the dove as soon as is convenient. But for the moment, they are doing what they feel they have to do to tamp expectations back to where they need them.
The Fed is undertaking this operation against inflation expectations despite waning liquidity. The graph below indicates the amount of money commercial banks hold in Fed accounts. It is a measure of the “ultimate” liquidity in the banking system.
It is trending down while the stock market trends up. This is risk, defined. Warsh/Bessent are wearing hawk costumes for now, but again, it’s a psy-op. I believe they know full well they will be inflating once again and this picture says they may be inflating against declining asset markets once the Semi bubble blows out and the market’s internal rotations find no more beat down areas to “play”.

Then – and now I am riffing – it comes back to gold. Amid liquidity crises with policymakers readying the inflation machinery gold is the first mover, likely with a silver bullet in its hip pocket. Why are the precious metals so on the outs right now while Semi mania, AI mania, Rocket mania, Kalshi mania and whatever other manias are out there finish up? Because they are preparing to lead to the upside, as they did to the downside. It’s not rocket science. Before Bessent advises a change of wardrobe for Warsh (hawk to dove costume) I expect gold to bottom and lead.
Stock Market
Meanwhile, it has been interesting and so far rewarding to stay in line with the market’s internal rotations.
The SOX index got croaked on Friday and the hits seem to be coming closer together now. Am I thinking of shorting it? Nope. I am not going to play that game. The SOX > NDX > SPX leadership chain is intact with SOX trending up vs. NDX and NDX still trending up vs. SPX.
Personally, I’d rather miss out on a shorting opportunity than risk going against these trends as long as they are intact.
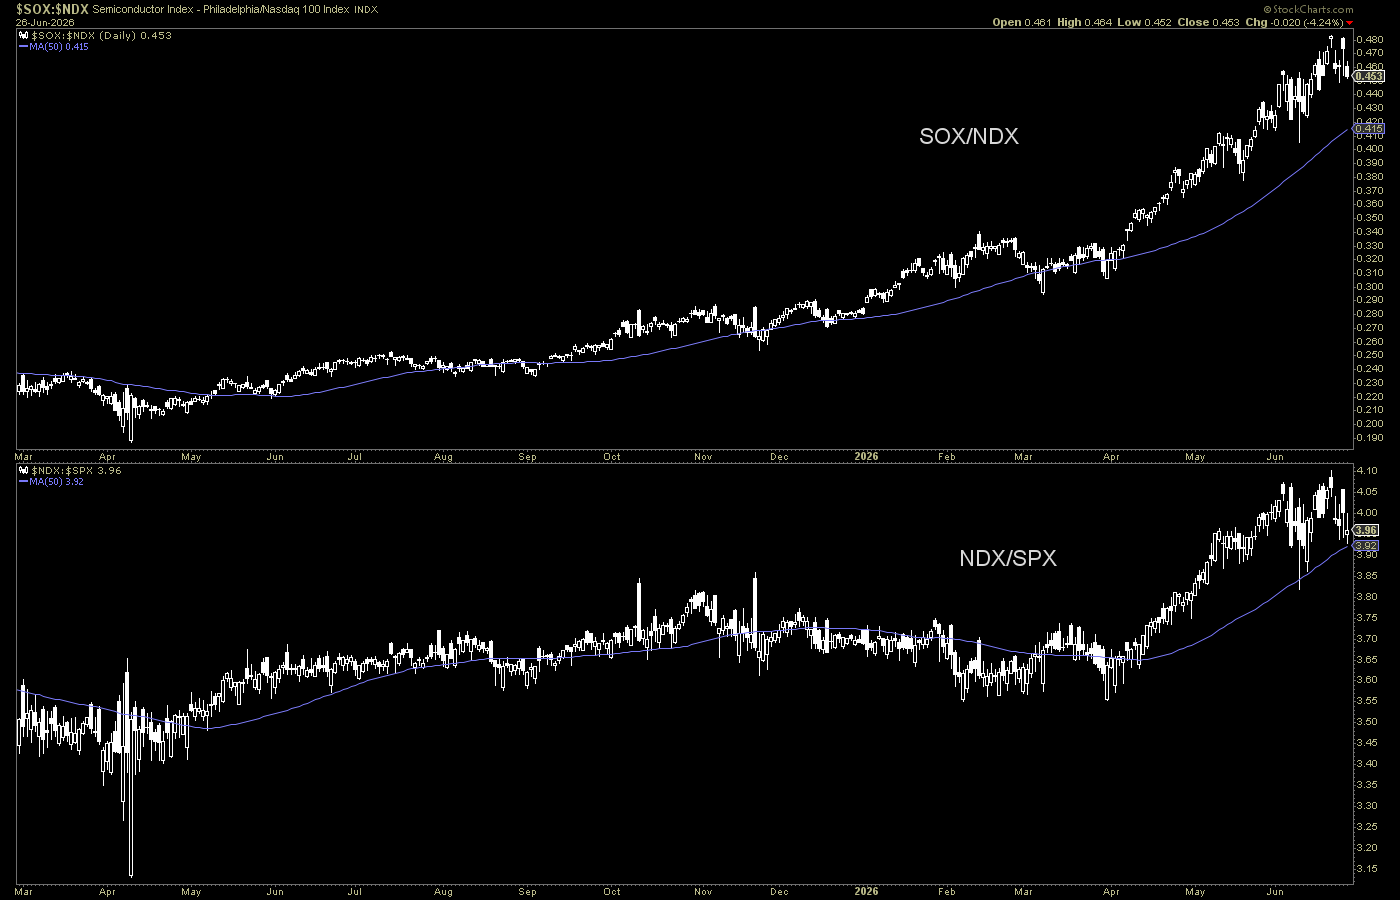
So what I want to continue to do is try to help us keep in touch with the market’s internal rotations. It’s a challenge, but on Friday it sure seemed like it was working out as Biotech continued upward…

…and Cloud/SaaS bounced hard from a valid support area.

Biotech/pharma holdings are GILD, NVO and LLY with ALNY, REGN, BEAM and BMRN added last week. I suppose you could include Psych stock CMPS in the ‘Bio’ group as well.
Here is my technical rationale for adding ALNY (long decline to clear support). My funda rationale is, as usual, born of other peoples’ micro research (as a SeekingAlpha contributor myself, I receive premium single-stock research). This frees me up so well to concentrate on the macro.

In the software space, I was shaken out of NOW and have it on watch along with a few others. Holdings are DDOG, MDB, DT and IOT, which we had previously noted to have sneaked out of a pattern, where I neglected to buy before it shot up after earnings. Well, it dropped back to that level and was added.

I’ll continue to respect support levels on these bottom feeds because I believe it is smarty pants quants and their algos rotating in. You know the types. Smartest guys in the room. I want to be aware of who I am running with.
That said, the software sector has been hammered and is due for some upside relief, in my opinion.
I blew an opportunity to finally regain position in Weed stock GLASF because I was not paying attention to it as it dive-bombed the 50 day average before turning back up again.

But I do still hold the sector (MSOS), GTBIF, CRON and as of last week TRLV, which has come back down after its spike (upon being listed on the NYSE). Let’s hope more such listings are in the offing, assuming rescheduling (hearings begin this week).

Global View
Interestingly, global stocks (ACWX) continue to look constructive for a real trend change to the upside vs. US stocks (SPY). The 200 day moving average (orange) has long-since turned up.

So what of the USD, which is normally inversely correlated to global stock market outperformance? Either the correlation is no longer as sure in the new macro, or the world is looking ahead to the end of this (likely) fake USD-supporting pretense by Warsh/Bessent.

Despite this, personally I am going to stick to what I see best, which is the US. I’ll keep an eye on some global, and may pick off an item here or there if opportunity arises. With ASML sold, I don’t think I have much global exposure now outside of Canada.
Impressions
- China: getting hammered.
- India: in a ‘W’ bounce pattern
- Europe: bullish
- UK: bullish
- Canada TSX: pure uptrend
- Canada TSX-V: still bearish
- LatAm 40: trending up but funky (suspect) pattern (Bovespa interesting after long decline)
- Asia/EM: trending up, knocked back of late (Hong Kong bearish, Singapore bullish, S. Korea hiccuping w/ Semi sector)
- Japan: bullish, extended
Commodities
A subscriber pinged me about NatGas and I am interested. AR and EQT are my two watch items. There are more. Please don’t take those as focused recos. The seasonal pattern says Gas may have bottomed. It typically sits flat until September and then turns up hard.

While I am suspect of commodities in general at the moment, I am keeping a close eye on uranium because I don’t want to get played out of the sector, which I think has compelling long-term supply/demand funda. To a degree I feel the same about rare earth, copper and battery materials stocks.
URNM has a gross looking chart, however. So I’ll keep watching (CCJ, NXE, UEC, UUUU, SRUUF, etc.) and take it week to week.

Market Sentiment
NAAIM: Over-bullish (contrary bearish) at 98.6%
AAII: Lurching over-bullish again at 45% bulls, 36% bears and 19% neutral. AAII do not often get this bullish (contrary bearish)
Fear/Greed Index: Yet the FGI ticks “Extreme Fear”. But here let’s understand that several of its components simply reflect market activity (weakening momentum, weakening stock prices, declining breadth). Put/Call ratios are spiking, which is contrary bullish. On balance, the components look more neutral than extreme anything.
High Yield Spreads: Still depressed, but did hook upward last week. If this starts rising we’ll likely have a real, honest to goodness market correction.

Portfolios
Gold is long-term risk management & monetary value/stability in a balanced portfolio.
Once again, no time for many words (lots of ’em in the report above) or notes in the tables. We’ve got my wife’s mom’s 80th birthday today and I’ve got to get motoring.

The “Savings” account will vary in its positioning. At times when I am confident of bullish markets it will hold positions, while remaining primarily a cash/equivalents account. At times I am not, it will not substantially hold much beyond cash/equivalents.
Trading Account
No positions.
Roth IRA (non-taxable, no contributions)
You know I take this chart seriously, and it is slithering along moderately bullish. But it has required a ton of effort to keep it intact in the face of tanking precious metals and commodities. More of the same required, or my risk management default is cash.

I am no longer able to sport gaudy 200%, 300% portfolio gains because I sold them all. I’d rather keep the chart above intact than bullshit you about long-term performance. With any luck, 2026-2027 could see a new phase of growing percentage gains once we clear the summer.
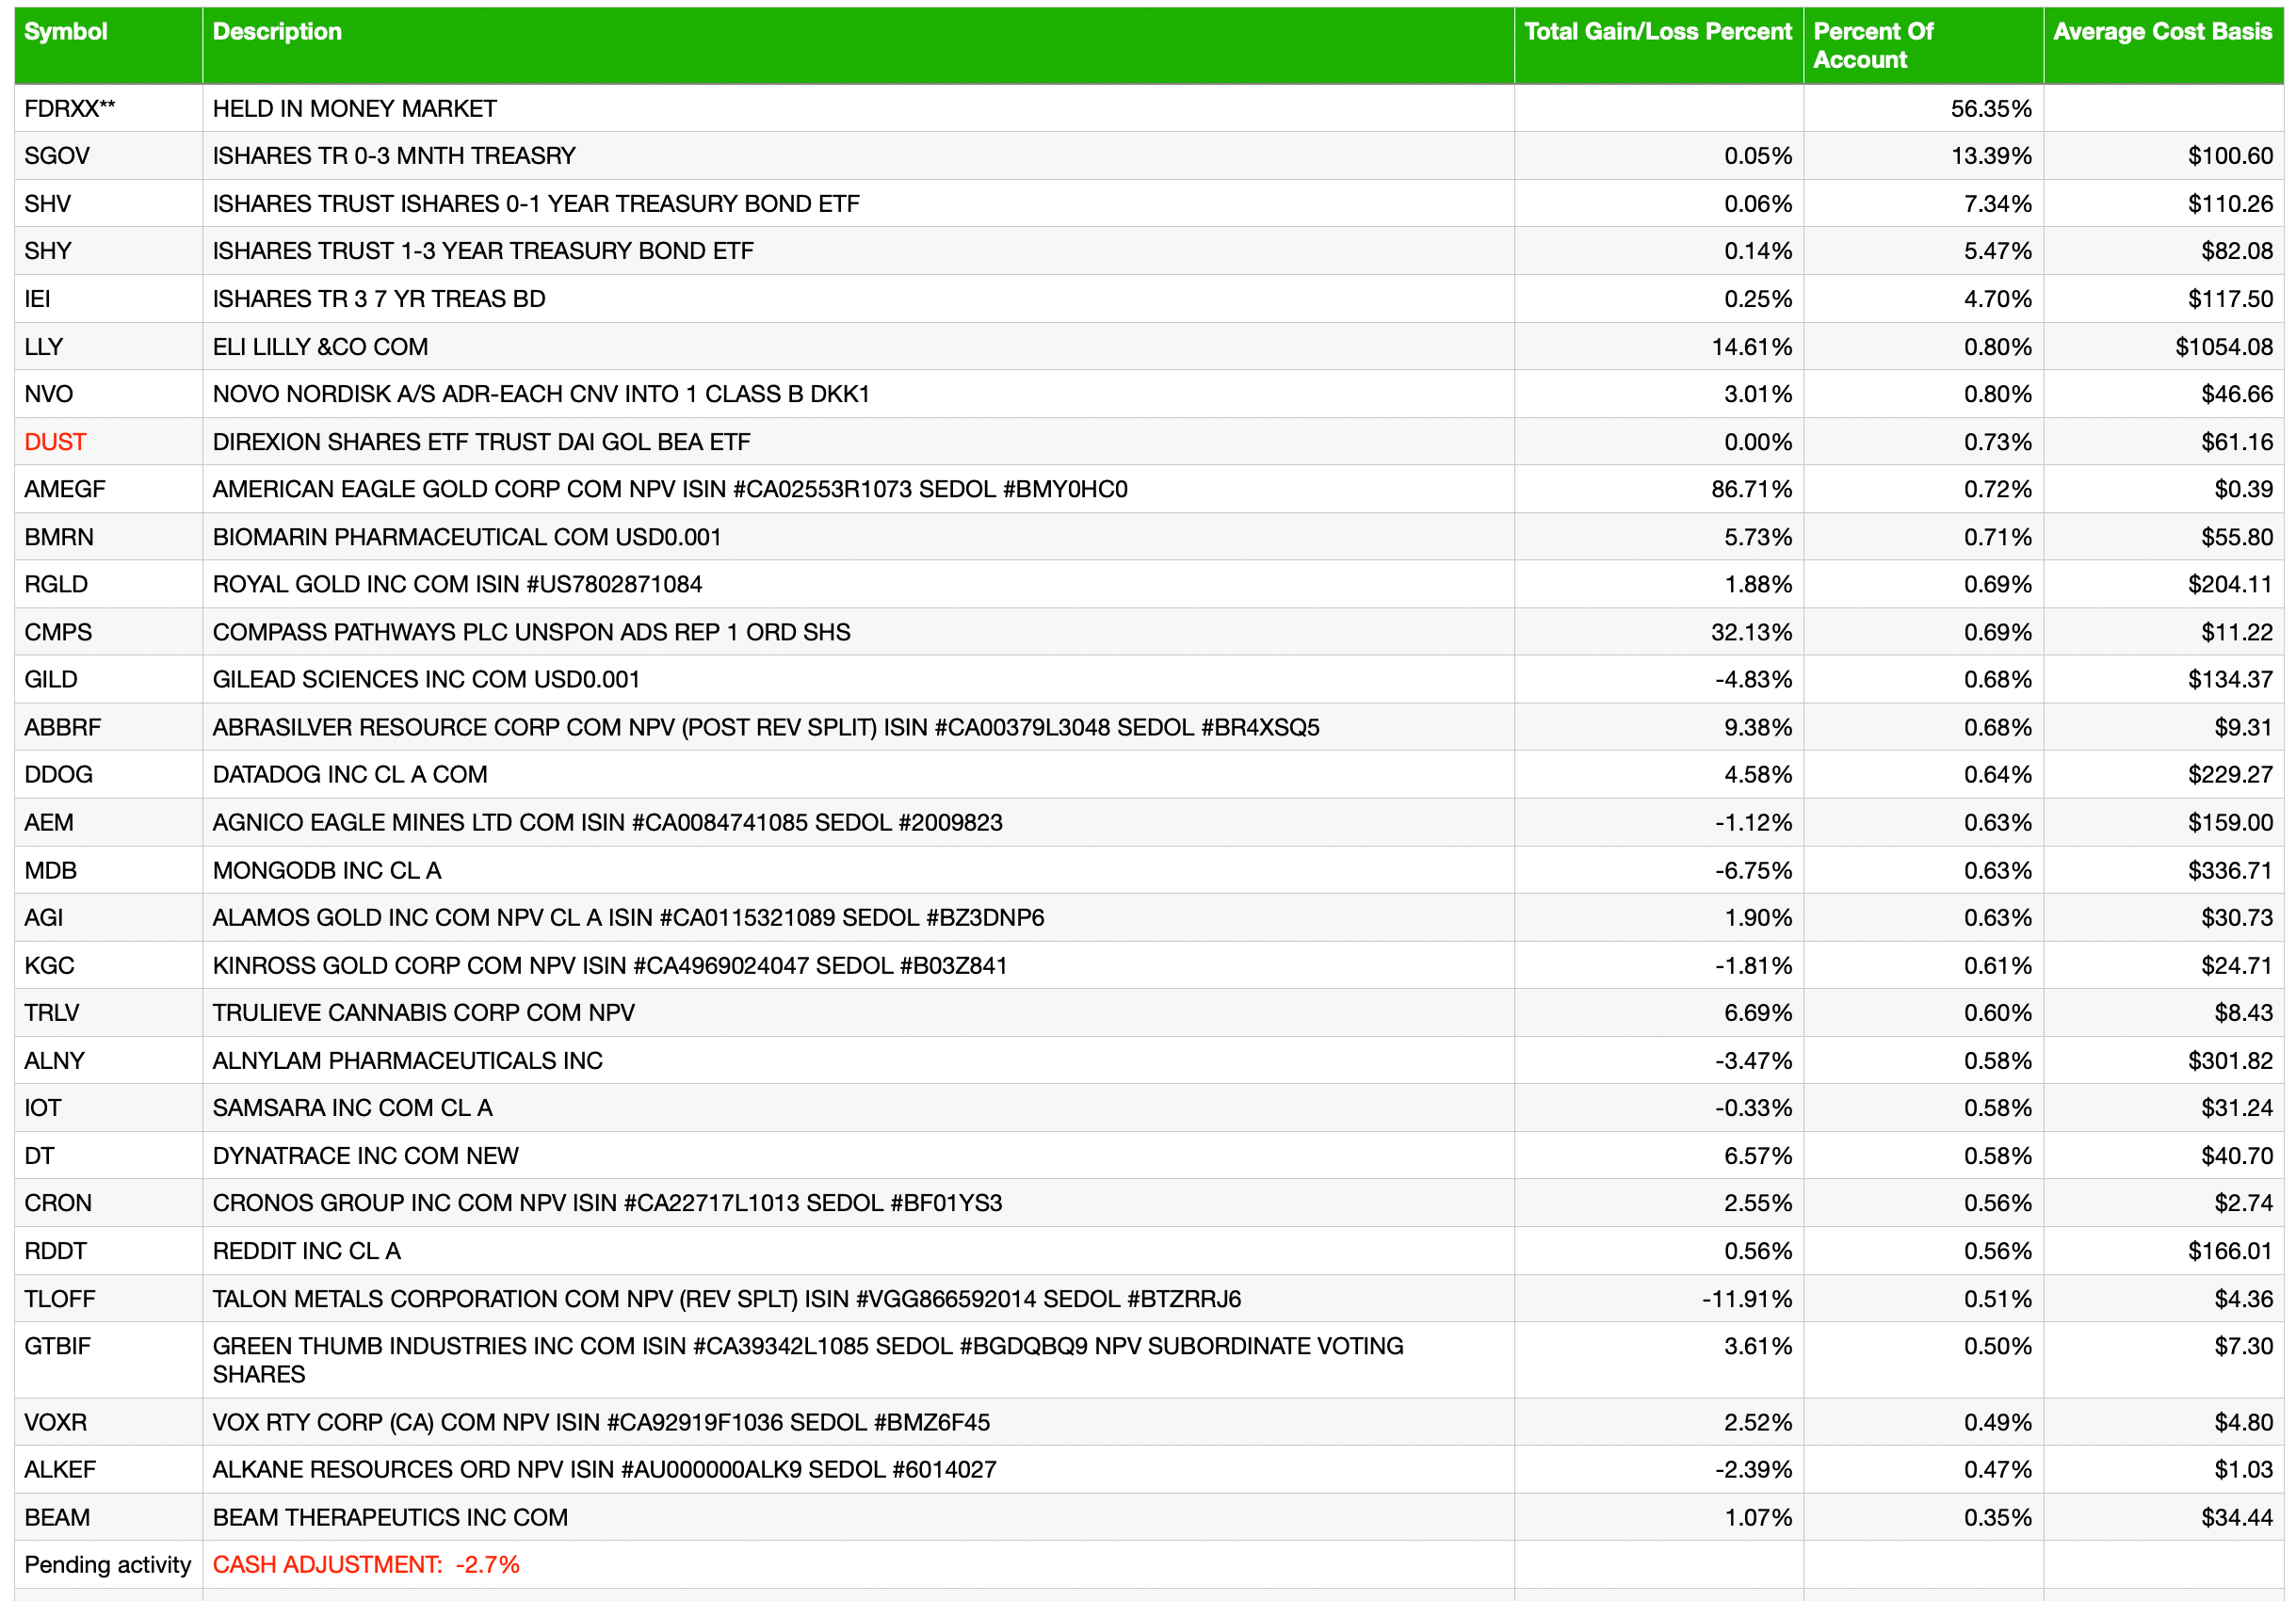
Cash & income-generating Treasury bonds are at levels that are right for me and my real-world situation. Your situation is different. Cash will be adjusted as needed.
Refer to the In-Week Notes under the NFTRH Premium menu at nftrh.com for market talk and occasional trading info, if interested. Also, you can follow on X @NFTRHgt for notice of updates.
NFTRH is not to be distributed to third parties without prior written consent
Notes From the Rabbit Hole (NFTRH) is a weekly market report in which we provide analysis on financial markets. We make every effort to provide accurate and high quality content, but this analysis ultimately represents our opinions and these opinions are provided without warranty or guarantee of any kind. See full terms & conditions of service under the ‘About’ heading in the main menu.

If/when the market corrects, what happens to gold/silver and what happens to miners? I am more of and investor as I am not nimble enough to be a trader……………….Dyrl
For the last several months gold has been busy decoupling from that risk as it declined and declined hard in SPX terms. That does not mean it would not go down if the broad market corrects, but IMO it strongly hints that relative strength would be shifted to gold. Also, it’s possible gold could rally as it did during much of the 2025 stock market correction.