
US Stock Market
This morning war is in the headlines again, yields and oil are up again, and the beat goes on. It almost seems scripted with the normal seasonal as well as the mid-term election cycle.
September is on average one of the worst months for the markets. During mid-term election years, it’s worse. But by early October things (on average) change for the much better. With full awareness that it can always be ‘different this time’, the broad market – as opposed to headline NDX & SPX – is following the script.

The above is SPX mid-term track record. SPX has outperformed the average this year. But we have been noting that market breadth has been poor (getting dangerous) as small caps and the broader stock market have been in correction mode (SPX Advance/Decline negative divergence, IWM/SPY ratio, Equal Weight SPX vs. Headline SPX, etc.) while the big names get a relative bid as the market’s internals rotate.
Here, for example, is the nominal small caps ETF, IWM. It is in a decent correction within a major uptrend. It is probably headed for a smack of the rising 200 day average, at least.

Where might the broad NYSE Composite bottom? The SMA 200 also.

So the broad market has been in correction into the early October window.
We are just a few days from the October window and I still think that Bessent is at work ‘fixing’ the situation. Yes war this, oil that, bond yields the other thing… but this is the stuff of (would-be) bottom-making. Bearishness and oversold markets, if that is what is upcoming, can provide fuel for a final push to the mid-terms.
The negativity is getting pretty thick out there but I don’t want to buy into it by shorting to any significant degree. Not until trends are broken and short setups emerge. As you can see, neither of the two charts currently in correction mode shown above has lost the uptrend.
It’s a thus far normal correction. I’ll manage risk with cash, as I will eliminate individual items if their charts do things I don’t like (like lose support), but be ready to buy as well.
Precious Metals
It’s whipsaw city, as I got shaken out of my hedges and consider it too late now, based on this morning’s projected open at 88.25. I thought it might be too neat for GDX to hold its converged moving averages. So why not lose the moving averages and maybe even fill the next gap while putting a hard test on support?

That false flag breakout last week was a bad omen. I will allow for a drop to the 84 area without getting too concerned. Remember, we are also allowing for the HUI/Gold ratio and GDX Advance/Decline to drop further before the next rally.
Also, while the sector internals are normal to good, the macro fundamentals are not good. Not with Treasury yields still ramping, war ongoing and oil spiking again. Speaking of yields, the “real” yield is making new highs, and that is traditionally bad for gold. So is the strong USD.

And gold is finally cracking. I have redrawn the flag to account for the failed breakout and now, the break down. Our view has been that the 2026 low is in. For that to prove out, gold will need to hold the 4030-4100 support area.
Incidentally, the flag is actually the right side of a little bearish looking pattern that would measure to around the 2026 low of 3942. As with the stock market, I think that the September-October seasonal can play out in gold and the precious metals sector with a concerning decline, over-bearish sentiment and an October rebound.

Silver is following gold below its 50 day average. Initial support is at 59.70. But a drop to the 56 area before a real rebound would not be at all surprising.

Welcome to the September seasonal pattern, only made worse by the mid-term election year September pattern. Only made worse by a war driven by an erratic man who’s playing war games and politics: we’ll bomb Iran after the mid-terms. What do the mid-terms have to do with war policy? Oh, right.
On the plus side, due to my thus far incorrect view (other than big Tech and Semi to a degree) that they would find a way to gun the markets into the mid-terms, the more fear and angst that is built up now, the better for a bullish view into and beyond the elections.
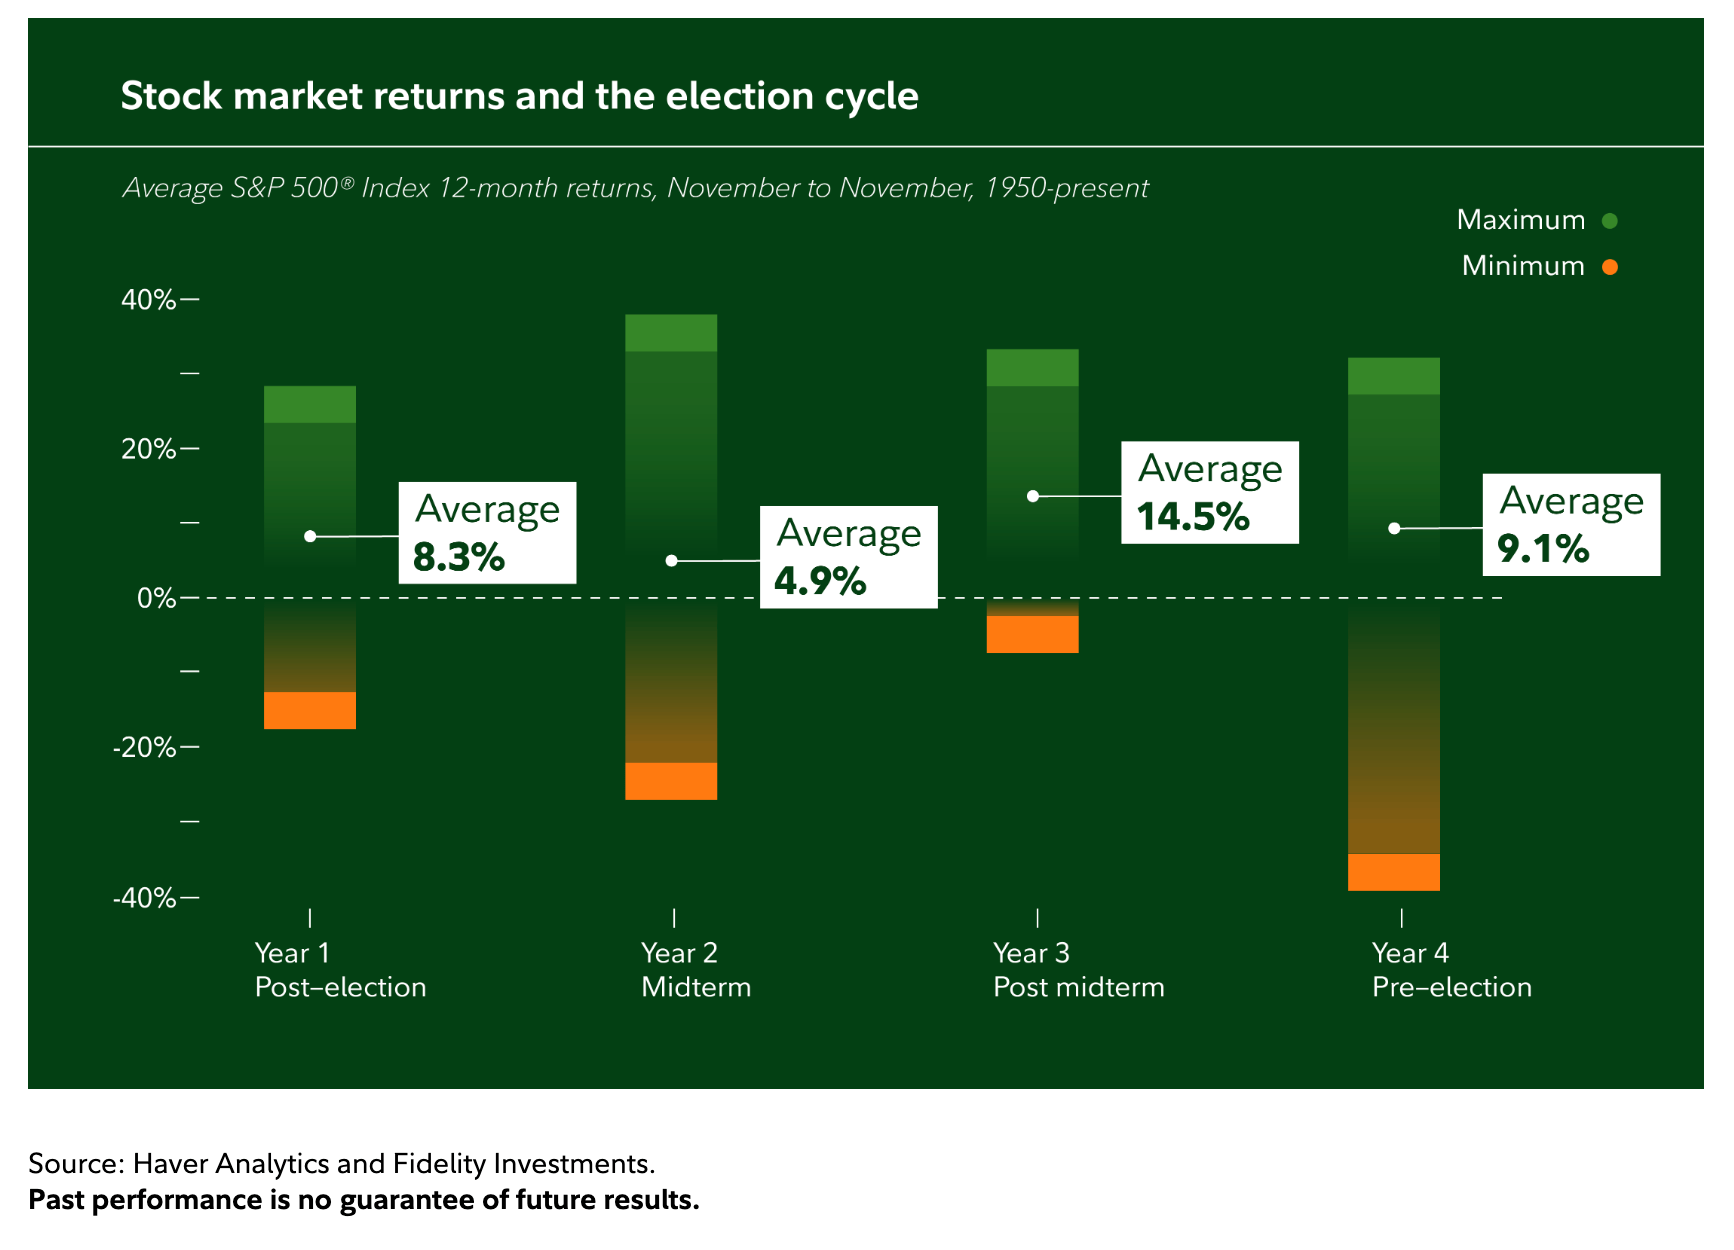
Having taken this opportunity to review mid-term years I am open to a buying opportunity for a more lasting market rally, pending about 9 million variables in play, of course. Including the fact that valuations are epic stretched and dangerous in historical terms.
But on the face of it, the post mid-term year is the best on average.
I have risk-managed to an acceptable degree (78% cash/equiv) in the savings account, and may have to raise more cash since it is a “savings” account and would just as soon appreciate the rising interest income in uncertain times.
I have risk managed to a fair degree (73% cash/equiv) in the IRA. Here too, I may trim out a thing or two. But more so, the focus is on finding a hard low in the next couple weeks and buying (sectors TBD).
I don’t think the funda will get much worse for gold and its miners. And if items like the USD and the real yields supporting it top out, and considering the sector’s internals, gold stocks will set up a significant buy opportunity. The larger macro is expected to be positive for gold and gold stocks after this phase completes.
Dat’s da view as of this bearish morning.

Exceptional report. Thank you Gary.